Of all the new home developments in the area, the one we are most tempted by is the Pulte Laurel Oaks development off Bass Lake Road in El Dorado Hills. They have single story homes, on nice sized lots, in a lovely little valley, and even managed to keep some of the existing oak trees.
Initially the prices were way too high and we had written them off our list. But they are close to finishing the development (which is a huge plus) and dropped their prices back in May to move the last couple homes, and added in some upgrades.
When we visited last time, we were incredibly tempted, but the lots weren't quite what we were looking for (odd slopes, angles etc). So it was a bit easier to pass up. At that time, there was a particular lot that I coveted, but it was already reserved. As with recent trends, the buyer pulled out....and now it's available.
When we sat down with the sales guy after looking at the home, the monthly quote he gave us was a bit surprising. It was considerably higher than we had calculated (his higher interest rate, my tax benefit inclusion). We could afford the payment, but it would really stretch us, and force us to change some of our spending/saving habits. It's also significantly higher than our current rent.
There are some not-so-minor financial issues. 20% on the home is a bit more than our current down payment, so we would have to get a loan from family to avoid PMI. Pulte won't pay our agents commission, which is really annoying, since I have been working with him for over a year to find a home. And, with all new homes, we would have to put in a backyard.
So basically, it all comes down to money, and how much we are willing to stretch. The home is everything we want, but money would be very tight in the short term. I'm just not sure the perfect home is worth the financial strain. Sigh.
Sunday, August 31, 2008


Friday, August 29, 2008
Between a rock and a hard place
Lots of talk about the Feds doing something (what we don't know) with Fannie (FNM) and Freddie (FRE). With all of the uncertainty surrounding the survivability of FNM/FRE, it has driven their cost of money up, which in turn has increased the cost of mortgages, which in turn has reduced the number of qualified buyers/borrowers, which in turn leads to lower home prices, which in turn leads to more write-offs at banks, which .... Well, you get the picture.
FNM and FRE have $223b (yes, billion) in short term debts, maturing in September (starting next week). They need to pay this debt off, probably with new debt. But it remains to be seen whether they can borrow this much new money (and at what cost), with the uncertainty hanging over their heads.
The pundits say that if the government intervenes, the common stock will be wiped out. At $5/share, I think that is a done deal ... Even Bear Stearns shareholders got $10/share! But what about the next level of shareholder, the holders of preferred shares? In the pecking order, preferred shares are above common shareholders, but below debt holders. The $64,000 question is, would a Fed action wipe out the preferred shareholders (who are currently collecting dividend yields from FNM/FRE in the range of 16%)? Would the Feds wipe out the equity of $36b of preferred shareholders?
Now, before you all say "don't bailout the preferred shareholders," many of those shareholders are banks, and the preferred shares represent as much as 16-34% of some banks tangible capital (GBTS, MBHI, WABC). In the case of Sovereign Bancorp, we are talking about +$800m of FNM/FRE preferred stock on its books. So if the preferreds aren't bailed out, then it is likely the FDIC will be taking over more banks (another kind of taxpayer funded bailout), as the banks' balance sheets are devastated with the writeoff of their preferred FNM/FRE stock holdings.
Paul
FNM and FRE have $223b (yes, billion) in short term debts, maturing in September (starting next week). They need to pay this debt off, probably with new debt. But it remains to be seen whether they can borrow this much new money (and at what cost), with the uncertainty hanging over their heads.
The pundits say that if the government intervenes, the common stock will be wiped out. At $5/share, I think that is a done deal ... Even Bear Stearns shareholders got $10/share! But what about the next level of shareholder, the holders of preferred shares? In the pecking order, preferred shares are above common shareholders, but below debt holders. The $64,000 question is, would a Fed action wipe out the preferred shareholders (who are currently collecting dividend yields from FNM/FRE in the range of 16%)? Would the Feds wipe out the equity of $36b of preferred shareholders?
Now, before you all say "don't bailout the preferred shareholders," many of those shareholders are banks, and the preferred shares represent as much as 16-34% of some banks tangible capital (GBTS, MBHI, WABC). In the case of Sovereign Bancorp, we are talking about +$800m of FNM/FRE preferred stock on its books. So if the preferreds aren't bailed out, then it is likely the FDIC will be taking over more banks (another kind of taxpayer funded bailout), as the banks' balance sheets are devastated with the writeoff of their preferred FNM/FRE stock holdings.
Paul
Thursday, August 28, 2008
Auburn Update
MCB44 was kind enough to send some updated statistics for Auburn. They continue to show the trends we were seeing back in April; more sales at the lower end of the market. This mimics what we are seeing in many areas of Sacramento, and largely accounts for the huge drop in the median price being reported by DataQuick (since the bulk of the home that are actually selling are at the lower end of the spectrum).
This skewed distribution can be seen by contrasting the recent OFHEO figures with DQ median (which is showing between 20%-35% drop depending on the county). The OFHEO data only shows a 17.68% drop in prices over the last year, and are still showing a 22% increase over the last 5 years.
From the Bee's Homefront Blog, OFHEO "is the national gold standard for measuring home prices. It reflects the same homes sold over time rather than the median, which lately tends to reflect the lowest end of the market activity with foreclosure properties."
I don't know too many who's wages have increased 22% over the last 5 years (the equivalent of getting a 5% raise each year)*.....its no wonder the buyer's still can't keep up.

* Of course I work at a not-for-profit, so those in the private sector may have done better in the boom years.
This skewed distribution can be seen by contrasting the recent OFHEO figures with DQ median (which is showing between 20%-35% drop depending on the county). The OFHEO data only shows a 17.68% drop in prices over the last year, and are still showing a 22% increase over the last 5 years.
From the Bee's Homefront Blog, OFHEO "is the national gold standard for measuring home prices. It reflects the same homes sold over time rather than the median, which lately tends to reflect the lowest end of the market activity with foreclosure properties."
I don't know too many who's wages have increased 22% over the last 5 years (the equivalent of getting a 5% raise each year)*.....its no wonder the buyer's still can't keep up.

* Of course I work at a not-for-profit, so those in the private sector may have done better in the boom years.
Tuesday, August 26, 2008
The more things change, the more they stay the same
The Mortgage Asset Research Institute reports that the number of fraudulent mortgages climbed 42% in the first quarter of 2008, compared to the first quarter of 2007. The most common fraud is employment history and overstated income. The biggest jump came from understated liens and judgments. Florida leads with 24% of the nation's total, with California in second place (and 52% of those in Los Angeles).
Apparently, with mortgages harder to obtain, folks are being less candid on their loan apps. So will we see these loans coming back in a few years as REO's?
I found it interesting to read on the actual fraud report, MARI's tag line, "Know your customer." What a novel idea for a modern business.
Paul
Apparently, with mortgages harder to obtain, folks are being less candid on their loan apps. So will we see these loans coming back in a few years as REO's?
I found it interesting to read on the actual fraud report, MARI's tag line, "Know your customer." What a novel idea for a modern business.
Paul
Monday, August 25, 2008
Privatized profits and socialized losses
Seems like that is where America is headed now. Today's estimates are that Fannie/Freddie will require $200 billion in bailouts. Detroit automakers want another $50 billion in bailouts. I have previously summarized hundreds of billions in bailouts via the Federal Reserve, Federal Home Loan Banks, etc. And if history is a guide, the estimates are going to be way too low, and the actual bailouts will be much higher. After all, if $50 billion to Detroit doesn't work, the gubmint is in too deep to not give them more if they need it. Same thing with Fannie/Freddie. I guess equally important is the fact that once the gubmint starts bailing, it must keep bailing regardless of the cost, because if it stops, it would be tantamount to an admission that maybe it wasn't a great idea in the first place, and of course, a "waste" of all that money already spent on the bailout.
Those printing presses much be humming 24 hours a day printing new money for all of these "gifts" from Washington.
Paul
Those printing presses much be humming 24 hours a day printing new money for all of these "gifts" from Washington.
Paul
Sunday, August 24, 2008
The Credibility Gap
Yesterday on the flight to D.C. I was catching up on my WSJ reading. I was on August 6th and read the article on FirstFed. It was very unsettling, even though I had seen the accompanying graphics on Calculated Risk earlier in the month.
This got me to wonder, why does an issue have a larger impact on me when I am physically holding a paper with a chart of the data, as opposed to reading it on the internet?
I don't really know the answer, but imagine it has something to do with human nature. Often a problem becomes much more "real" when you or someone you know is directly affected by it.
Or could it be, that I had the time to sit and read every word of the article (as opposed to my usual skimming online) and absorb the true impact of what they were saying? Perhaps on the internet, there is just too much information vying for our attention. Which, in the end, results in nothing keeping our attention? To be fair, I was on deadline that week (hence the unread WSJ).
In any event, this is a pretty big deal (which many bubble bloggers already know about). In my immediate circle of friends and family I know of at least 3 folks with ARMs due to reset in the next two years. While many are calling bottom for the low end in Sacramento, I think the party is just getting started on the higher end.
Random note about queuing: At work I am surrounded by Operations Research folks, so queuing is very serious business. I use use LIFO when it comes to my reading stack. That way, all the articles anticipating an event don't need to get read, since I am reading how it was resolved before I even get to the earlier articles. As obsessive as I am about my WSJ reading and housing stats, I am actually a pretty laid back in most other respects.
This got me to wonder, why does an issue have a larger impact on me when I am physically holding a paper with a chart of the data, as opposed to reading it on the internet?
I don't really know the answer, but imagine it has something to do with human nature. Often a problem becomes much more "real" when you or someone you know is directly affected by it.
Or could it be, that I had the time to sit and read every word of the article (as opposed to my usual skimming online) and absorb the true impact of what they were saying? Perhaps on the internet, there is just too much information vying for our attention. Which, in the end, results in nothing keeping our attention? To be fair, I was on deadline that week (hence the unread WSJ).
In any event, this is a pretty big deal (which many bubble bloggers already know about). In my immediate circle of friends and family I know of at least 3 folks with ARMs due to reset in the next two years. While many are calling bottom for the low end in Sacramento, I think the party is just getting started on the higher end.
Random note about queuing: At work I am surrounded by Operations Research folks, so queuing is very serious business. I use use LIFO when it comes to my reading stack. That way, all the articles anticipating an event don't need to get read, since I am reading how it was resolved before I even get to the earlier articles. As obsessive as I am about my WSJ reading and housing stats, I am actually a pretty laid back in most other respects.
Friday, August 22, 2008
Circling In
When we moved into our rental in the Fall of 2006, we signed a 6 month lease. We figured that would give us plenty of time to get reacquainted with the area and purchase a home. At the time, I was open to living in almost any family friendly part of Sacramento that had reasonable public schools.
Little did we know, we would still be renting the same home almost 2 years later. During this time, we have made friends, become active in local groups, and basically settled into the community.
As a result, I find myself wanting to purchase a home closer and closer to where we live now. In other words, my home searching radius is getting smaller the longer we stay here.
At this rate, if we are still here in another 2 years, I may have to talk Mr. BT into purchasing our rental home =)
Little did we know, we would still be renting the same home almost 2 years later. During this time, we have made friends, become active in local groups, and basically settled into the community.
As a result, I find myself wanting to purchase a home closer and closer to where we live now. In other words, my home searching radius is getting smaller the longer we stay here.
At this rate, if we are still here in another 2 years, I may have to talk Mr. BT into purchasing our rental home =)
Thursday, August 21, 2008
July August 2008 Month's Inventory
Wow, month's inventory is still shrinking! We are now down below 4 months for the Sac Metro area. And while some of the pricey zips still appear to have a high month's inventory, in reality, lower priced homes are in short supply, while the expensive ones sit for what seems like an eternity.
This is good news, and proof that the market is working its way towards equilibrium. It also proves that buyers are out there, so its merely a matter of the market finding price levels that buyers can afford. If they price it right...the buyers will come.

This is good news, and proof that the market is working its way towards equilibrium. It also proves that buyers are out there, so its merely a matter of the market finding price levels that buyers can afford. If they price it right...the buyers will come.

Wednesday, August 20, 2008
Riddle Me This?
How can a home, which has been sitting on the MLS for almost a year, and at the current price for 4 months, without ANY offers, recently appraise at 97% of the value?
I obviously don't understand real estate......
We agreed to pay for an appraisal for the short sale we put an offer on, in order to convince the bank that it wasn't worth what they wanted. The appraisal came in much higher than our offer (which was about 10% off list....our previous offer was 95% off list when interest rates were lower).
Supposedly, the home is now going to go into foreclosure. It will be interesting to see if we are able to purchase it then....
In the mean time, many homes in my favorite neighborhood have come on the market. Two at prices we can afford, and the rest way above our means.
I obviously don't understand real estate......
We agreed to pay for an appraisal for the short sale we put an offer on, in order to convince the bank that it wasn't worth what they wanted. The appraisal came in much higher than our offer (which was about 10% off list....our previous offer was 95% off list when interest rates were lower).
Supposedly, the home is now going to go into foreclosure. It will be interesting to see if we are able to purchase it then....
In the mean time, many homes in my favorite neighborhood have come on the market. Two at prices we can afford, and the rest way above our means.
Tuesday, August 19, 2008
Defying Gravity
Zillow came out with some interesting study results this month. Seems most homeowners think that, while home prices are falling in general, their home value is not (as the article points out, its akin to everyone thinking their IQ is above average).
According to ForeclosureRadar, on my street there are:
According to ForeclosureRadar, on my street there are:
- 5 homes in preforeclosure
- 2 bank owned homes
- 2 homes slated for auction
- 7 homes listed on the MLS (3 of which are PS), which includes some of the home listed above.
Monday, August 18, 2008
Update: Driving Home the Debt
A couple months ago I did a post on the WSJ's monthly "hottest models." As some may recall, I was flabbergasted by the price tag on these cars that were so popular.
In another sign of the times, the July 2008 list is a very different list. This time, only three cars had price tags over 30K, as opposed to the vast majority in Feb/Mar. The average price tag for all the models listed has fallen around 28% compared to the earlier time frame!
Not surprisingly, the Toyota Prius tops the list (it was also the only car under 30K on the list in March).
In another sign of the times, the July 2008 list is a very different list. This time, only three cars had price tags over 30K, as opposed to the vast majority in Feb/Mar. The average price tag for all the models listed has fallen around 28% compared to the earlier time frame!
Not surprisingly, the Toyota Prius tops the list (it was also the only car under 30K on the list in March).
It's Negotiable
Was delighted to see that one of my favorite publications, Consumer Reports (who would have guessed ;) did a recent survey on real estate.
Below is a very interesting conclusion from their study, which is good news for both buyers and sellers (hat tip to the WSJ Developments blog):
"Many real-estate brokers are willing to cut a deal on their commissions, and readers who successfully negotiated for a lower commission, often cutting the traditional 6 percent to 3 or 4 percent, tended to be just as satisfied with the result as those who paid the full fare."
If I had my way, I would completely redesign the compensation system. Here are my thoughts on how commissions should be structured.
Below is a very interesting conclusion from their study, which is good news for both buyers and sellers (hat tip to the WSJ Developments blog):
"Many real-estate brokers are willing to cut a deal on their commissions, and readers who successfully negotiated for a lower commission, often cutting the traditional 6 percent to 3 or 4 percent, tended to be just as satisfied with the result as those who paid the full fare."
If I had my way, I would completely redesign the compensation system. Here are my thoughts on how commissions should be structured.
Friday, August 15, 2008
A Huge Sigh of Relief
This is my virtual sigh of relief. The week is ending with oil down to $113 a barrel, and the dollar gaining ground. I feel we are now in manageable territory. At this price, industries and consumers should be able to cope.
At $147 a barrel, I believe we were facing economic implosion. The economy was already limping due to housing woes and the credit crunch.....expensive oil and commodities would have been the fatal shot to the heart.
This is not to say we should throw a party. $113 will still be tough going for many industries, like aviation, but 23% is certainly worth a sigh of relief.
At $147 a barrel, I believe we were facing economic implosion. The economy was already limping due to housing woes and the credit crunch.....expensive oil and commodities would have been the fatal shot to the heart.
This is not to say we should throw a party. $113 will still be tough going for many industries, like aviation, but 23% is certainly worth a sigh of relief.
Street spam
Is your neighborhood inundated with illegal advertising signs on every corner? The question I have is, who's job is it to remove them? We know the criminals (if you put up an illegal sign, presumably you are a criminal) aren't going to remove the signs.
Although the signs are illegal, Cameron Park Community Services District tells me 'there is nothing we can do about them.' (Of course, IMO, not true, but that is a blog for a different day.)
In addition to being an eyesore, the signs eventually become more litter in our fields and gutters as they are blown down by the wind and weather, most of which appear to have a biodegradable 1/2 life of about 500,000 years, due to the fact they are frequently made of plasticized something-or-other.
I'm not talk about election signs (which are also an eyesore, but protected under the Constitution), or bonafide local real estate signs, or even neighborhood garage sale/lost cat/found dog signs. I'm talking about "Earn millions working from home," "Bankrupty Lawyer" (one of my personal favorites), "We Buy Houses!," "Avoid Foreclosures," Whole House Fans," Humane Rattlesnake Removal," "XYZ Gym and Fitness in Folsom," and so many more.
The Cameron Park area that I drive in is virtually free of the signs. (Wish I could say the same for the portions of EDH and Folsom that I see.) Of course, the criminals still put up the signs, but with apparently less enthiusiasm than time past. I've heard, but have no way of verifying if true, of course, that someone in CP stops his/her car when they see and illegal sign, and picks the sign up for later recycling.
Perhaps if their signs disappear from the horizon as fast as the criminals put them up, word will get out and the criminals will move on, thus making our neighborhoods look more like neighborhoods than litter-bound eyesores.
Just my opinion.
Paul
P.S. Did you know there are actually blogs devoted to street spam, tools for removing street spam, legal issues, etc? Heck, a short while ago, I didn't even know what "street spam" was!
Although the signs are illegal, Cameron Park Community Services District tells me 'there is nothing we can do about them.' (Of course, IMO, not true, but that is a blog for a different day.)
In addition to being an eyesore, the signs eventually become more litter in our fields and gutters as they are blown down by the wind and weather, most of which appear to have a biodegradable 1/2 life of about 500,000 years, due to the fact they are frequently made of plasticized something-or-other.
I'm not talk about election signs (which are also an eyesore, but protected under the Constitution), or bonafide local real estate signs, or even neighborhood garage sale/lost cat/found dog signs. I'm talking about "Earn millions working from home," "Bankrupty Lawyer" (one of my personal favorites), "We Buy Houses!," "Avoid Foreclosures," Whole House Fans," Humane Rattlesnake Removal," "XYZ Gym and Fitness in Folsom," and so many more.
The Cameron Park area that I drive in is virtually free of the signs. (Wish I could say the same for the portions of EDH and Folsom that I see.) Of course, the criminals still put up the signs, but with apparently less enthiusiasm than time past. I've heard, but have no way of verifying if true, of course, that someone in CP stops his/her car when they see and illegal sign, and picks the sign up for later recycling.
Perhaps if their signs disappear from the horizon as fast as the criminals put them up, word will get out and the criminals will move on, thus making our neighborhoods look more like neighborhoods than litter-bound eyesores.
Just my opinion.
Paul
P.S. Did you know there are actually blogs devoted to street spam, tools for removing street spam, legal issues, etc? Heck, a short while ago, I didn't even know what "street spam" was!
Thursday, August 14, 2008
The Growing Gap
I haven't reported on my screen scrape in some time. Several interesting things of note.
The number of homes pending sale has jumped again. We just hit a new record high, at my scrape yesterday. While the total number of homes meeting my criteria is still very high, the pending sale, and short sale homes make up the bulk of the listings these days. The list price differentials between the categories is what is the most interesting.
Average list price per square foot for homes in Folsom and EDH that meet my criteria -
Pending Sale -$174
Short Sale - $174
REO & Normal - $189
Thus, even though there are tons of homes for sale in the area, there is very little of interest on the market worth pursuing, except a couple REOs. We are attempting to negotiate a short sale, but my expectations are very low at this point.
The number of homes pending sale has jumped again. We just hit a new record high, at my scrape yesterday. While the total number of homes meeting my criteria is still very high, the pending sale, and short sale homes make up the bulk of the listings these days. The list price differentials between the categories is what is the most interesting.
Average list price per square foot for homes in Folsom and EDH that meet my criteria -
Pending Sale -$174
Short Sale - $174
REO & Normal - $189
Thus, even though there are tons of homes for sale in the area, there is very little of interest on the market worth pursuing, except a couple REOs. We are attempting to negotiate a short sale, but my expectations are very low at this point.
Wednesday, August 13, 2008
Updated Market Stress for Folsom and El Dorado Hills
Below is the updated market stress data for Folsom and El Dorado Hills. The NODs had leveled off for both zips for a while, but this week saw a renewed upward trend. I included some additional data this week for context, such as REOs listed on Metrolist (which includes the REOs that are Pending Sale), to get a feel for the level of shadow inventory as discussed on SacRealStats.
I should note that none of these data sets are complete, and they don't all necessarily overlap the way they should. But I think the magnitude of the data is about right, and that relative comparisons can still be made. For example, the SFH listings, from ZipRealty could be subtracted from the Total MLS listings, to get a relative feel for how many homes are currently pending sale in each zip. The REOs could be subtracted from the foreclosures to determine the level of "shadow" inventory etc.
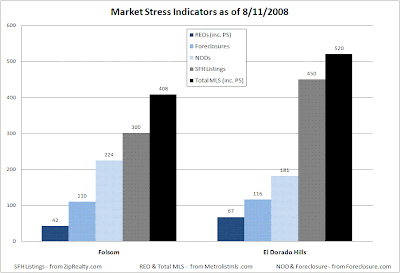
I should note that none of these data sets are complete, and they don't all necessarily overlap the way they should. But I think the magnitude of the data is about right, and that relative comparisons can still be made. For example, the SFH listings, from ZipRealty could be subtracted from the Total MLS listings, to get a relative feel for how many homes are currently pending sale in each zip. The REOs could be subtracted from the foreclosures to determine the level of "shadow" inventory etc.

Tuesday, August 12, 2008
Bemoaning the Budget
Since budgets are all the talk right now in Sacramento, I thought it would be a good topic for the day.
When average folks have a goal, like home ownership or early retirement, the standard advise seems to be "make a budget". To me this is a lot like the "food diary" advise for weight loss. Nice in theory, but just way to intrusive and hard to keep up for a busy family.
I do reconcile our credit cards, bank statements, etc. in Quicken every couple months. I also categorize the purchases, but there are many items that fall outside a normal budget (like loans to family, or work expenses), or ATM cash that just disappeared. I have tried on several occasions to use the budgeting functionality in Quicken, but for some reason or another, it doesn't get me what I am looking for.
This leads me to wonder, does anyone actually have a household budget and if so, do you follow it?
There are many categories, in which I am unsure about how much to budget. For instance, how much to give to charity, how much should we allocate in gifts to family and friends, how much for travel and vacations?
Both Mr. BT and I grew up in families that struggled to pay for basics like food and clothes during some periods of our lives. This environment shaped our financial habits. We don't buy on credit unless we can pay off the bills immediately. Now that our massive student loans are paid off, we have relaxed the reigns a bit and spend a bit more freely.
I have an idea how much we spend on things, but I don't know if its above average, or if we are really pinching pennies. Talking to my uncle, who's family makes considerably less than us, I feel like we really pinch pennies on things like food, auto and cable bills compared to them. But I don't know if they are over spending, or if we are underspending.
With finances a somewhat taboo subject among friends and colleagues....how do people figure this stuff out?
When average folks have a goal, like home ownership or early retirement, the standard advise seems to be "make a budget". To me this is a lot like the "food diary" advise for weight loss. Nice in theory, but just way to intrusive and hard to keep up for a busy family.
I do reconcile our credit cards, bank statements, etc. in Quicken every couple months. I also categorize the purchases, but there are many items that fall outside a normal budget (like loans to family, or work expenses), or ATM cash that just disappeared. I have tried on several occasions to use the budgeting functionality in Quicken, but for some reason or another, it doesn't get me what I am looking for.
This leads me to wonder, does anyone actually have a household budget and if so, do you follow it?
There are many categories, in which I am unsure about how much to budget. For instance, how much to give to charity, how much should we allocate in gifts to family and friends, how much for travel and vacations?
Both Mr. BT and I grew up in families that struggled to pay for basics like food and clothes during some periods of our lives. This environment shaped our financial habits. We don't buy on credit unless we can pay off the bills immediately. Now that our massive student loans are paid off, we have relaxed the reigns a bit and spend a bit more freely.
I have an idea how much we spend on things, but I don't know if its above average, or if we are really pinching pennies. Talking to my uncle, who's family makes considerably less than us, I feel like we really pinch pennies on things like food, auto and cable bills compared to them. But I don't know if they are over spending, or if we are underspending.
With finances a somewhat taboo subject among friends and colleagues....how do people figure this stuff out?
Sunday, August 10, 2008
The Family Treehouse
Here is a quick rundown on how my immediate family has been affected by the housing bubble. Increased affordability has helped my mom and dad (separately) become homeowners again, but unfortunately it will be a struggle for my younger brother to hold on to his home.
- Mom, Santa Maria CA, just bought a home with her long time boyfriend, paid cash, retired.
- Brother, Aliso Viejo CA, has lost all equity on the home he and is wife purchased in 2005. Their ARM will adjust in 2 years, to approximately 50% their income. It will be difficult to work something out with the bank since they took out a 2nd when purchasing the home.
- Father, Puerto Vallarta/Stocton CA, moved to Mexico from Stockton around 5 years ago, now purchasing a bank owned home in Stockton. Currently under contract. Retired.
Friday, August 8, 2008
It's Even More Official
The job losses are mounting.
My uncle, the printer, who has been living in the Sacramento area for almost 20 years, tied the knot this year. Unfortunately, the good times were sort lived. I am deeply saddened to report that his new wife, has been laid off without warning, after working at a local Sacramento business for 19 years.
She is the second family member in the area to be laid off recently.
I am at a loss for words to describe how I feel right now.
My uncle, the printer, who has been living in the Sacramento area for almost 20 years, tied the knot this year. Unfortunately, the good times were sort lived. I am deeply saddened to report that his new wife, has been laid off without warning, after working at a local Sacramento business for 19 years.
She is the second family member in the area to be laid off recently.
I am at a loss for words to describe how I feel right now.
August 2008 Inventory
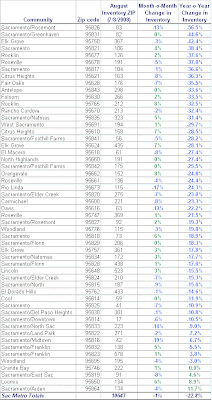
Inventory is somewhat steady compared to last month, but is still down 22% compared to last year. This month's data is sorted by the biggest drop compared to last year. Data was collected from ZipRealty site for SFHs. The increases are in green, and decreases are in blue.

Thursday, August 7, 2008
Sacramento Airport Activity Reflects the Region's Troubles
Max over at SacRealStats has been documenting his experience at several airports in CA.
Since aviation is my industry, I thought I would take a quick peak at our regions airport statistics for June of 2008, which is the most recent data they have on their webpage: http://www.sacairports.org/int/about/stats.htm
I don't have good news to report. Activity at our local airports is experiencing substantial declines. This is not a good sign for our region and our economy.
Sacramento International -
Passenger traffic is down 6.4% over last year.
Operations are down 10.4%.
Mather Field -
Operations are down a whopping 25.2% (with general aviation taking the biggest hit)
And operations at Sacramento Executive Airport are down 15.7%.
Update: I just checked the FAA's Terminal Area Forecast....from 2007 to 2008, SMF was actually supposed to grow operations by 2.3%! I guess we will be seeing some revised forecasts.
Since aviation is my industry, I thought I would take a quick peak at our regions airport statistics for June of 2008, which is the most recent data they have on their webpage: http://www.sacairports.org/int/about/stats.htm
I don't have good news to report. Activity at our local airports is experiencing substantial declines. This is not a good sign for our region and our economy.
Sacramento International -
Passenger traffic is down 6.4% over last year.
Operations are down 10.4%.
Mather Field -
Operations are down a whopping 25.2% (with general aviation taking the biggest hit)
And operations at Sacramento Executive Airport are down 15.7%.
Update: I just checked the FAA's Terminal Area Forecast....from 2007 to 2008, SMF was actually supposed to grow operations by 2.3%! I guess we will be seeing some revised forecasts.
Market Manipulation
As many of you know, I have a strong hunch that Wall Street insiders and speculators are responsible for many of our recent bubbles (they manipulate the market and make a killing at the expense of the "ignorant masses").
This recent revelation by Reuters does little to quell my conspiracy theory leanings....
"A quiet data revision that has boosted by nearly 25 percent the number of oil futures contracts U.S. regulators think are held by speculators is raising eyebrows in the energy trading community. The revision means that speculators controlled 48 percent of the open interest in NYMEX crude oil futures and options as of July 15, compared with just over 38 percent under the previous classification.......The big shift is all the more surprising, oil traders and analysts said, since the CFTC apparently reclassified only one unidentified oil trader at the same time as the data revision."
I am quickly losing confidence that our free market society provides equal benefits to all involved. U.S. regulations and over site are out of date, and too disjointed to properly monitor the market and ensure that it is free of manipulation. Those with connections and resources routinely increase their wealth, while those without are left to foot the bill for the market's excessive risk taking.
This recent revelation by Reuters does little to quell my conspiracy theory leanings....
"A quiet data revision that has boosted by nearly 25 percent the number of oil futures contracts U.S. regulators think are held by speculators is raising eyebrows in the energy trading community. The revision means that speculators controlled 48 percent of the open interest in NYMEX crude oil futures and options as of July 15, compared with just over 38 percent under the previous classification.......The big shift is all the more surprising, oil traders and analysts said, since the CFTC apparently reclassified only one unidentified oil trader at the same time as the data revision."
I am quickly losing confidence that our free market society provides equal benefits to all involved. U.S. regulations and over site are out of date, and too disjointed to properly monitor the market and ensure that it is free of manipulation. Those with connections and resources routinely increase their wealth, while those without are left to foot the bill for the market's excessive risk taking.
Wednesday, August 6, 2008
We can Out-Wait, but can we Out-Wit?
Some may remember the short sale we agonized over this spring. In the end we decided not to go up in price and meet the bank's price. Our waiting strategy may pay off yet. After many months of sitting at the bank's (first loan's) price, we are going to resubmit our offer (albeit adjusted for the increase in interest rates).
Last Sunday we did see an REO that is amazing, and in our price range (the one on Moonstone in EDH). But they want us to go through all kinds of prequal and legal hoops, and the bank who owns it is Option One (not excited about dealing with them again). Our realtor figures it will go for much more than asking, so we are not inclined to go through all the hassle in order to get outbid.
I am also kinda still kicking myself that we didn't go up a bit on the last REO we bid on. It was basically in move in condition with lots of gorgeous tile and granite work. Sigh.
Last Sunday we did see an REO that is amazing, and in our price range (the one on Moonstone in EDH). But they want us to go through all kinds of prequal and legal hoops, and the bank who owns it is Option One (not excited about dealing with them again). Our realtor figures it will go for much more than asking, so we are not inclined to go through all the hassle in order to get outbid.
I am also kinda still kicking myself that we didn't go up a bit on the last REO we bid on. It was basically in move in condition with lots of gorgeous tile and granite work. Sigh.
Sunday, August 3, 2008
As the Endgame Draws Near
According to Webster's "endgame" is the final stage of a game of chess, usually following the exchange of queens and a serious reduction of forces. This term seems appropriate for the eventual fate of this blog as well as many other RE bubble sites.
In that past couple months, many longtime bubble bloggers have purchased, or are currently purchasing a home, as prices in the Sacramento area have come back down to earth.
This leads me to wonder, what is going to happen to the vibrant community of bubble bloggers? Looking at all the links on Lander's site, its a sizable cottage industry =)
As for this blog, sometime in the short term, we hope to buy a home. If we don't, I suspect it will get really lonely around here, as many will have preceded us.
But what I am really curious about is the long term. In the long term, all the housing bubble sites will be obsolete. I suppose some sites with a large economic base, like CalculatedRisk, could evolve with the times.
Obsolesce is awkward. It's like the mom's I see around here, who, instead of aging gracefully, are still trying desperately to be hip and young.
When my time comes, I already know it will be hard to let go of something I have diverted so much energy and time to. This waiting game is a lot like being pregnant. The end product makes the wait worth the while (although this time we have waited longer than both pregnancies combined!).
In that past couple months, many longtime bubble bloggers have purchased, or are currently purchasing a home, as prices in the Sacramento area have come back down to earth.
This leads me to wonder, what is going to happen to the vibrant community of bubble bloggers? Looking at all the links on Lander's site, its a sizable cottage industry =)
As for this blog, sometime in the short term, we hope to buy a home. If we don't, I suspect it will get really lonely around here, as many will have preceded us.
But what I am really curious about is the long term. In the long term, all the housing bubble sites will be obsolete. I suppose some sites with a large economic base, like CalculatedRisk, could evolve with the times.
Obsolesce is awkward. It's like the mom's I see around here, who, instead of aging gracefully, are still trying desperately to be hip and young.
When my time comes, I already know it will be hard to let go of something I have diverted so much energy and time to. This waiting game is a lot like being pregnant. The end product makes the wait worth the while (although this time we have waited longer than both pregnancies combined!).
Covered bonds, the next taxpayer bailout
Although too long and probably not suitable for including in a post, you are all encouraged to read "Covered Bonds, Exposed Taxpayers" in the current issue of Business Week. As sure as bears use Charmin in the woods, this will come back to bite us in the future.
In short, banks issue mortgage back bonds to finance real estate loan purchases. The loans remain on the banks' balance sheets, thus, if the bank fails, the loans are repaid to the investors ahead of payments to the FDIC. If there are insufficient assets to repay the FDIC, the FDIC takes another financial hit. Enough financial hits to the FDIC, and we are back to the taxpayer paid S&L bailout of 1990. FDIC Sheila Bair, who is a very bright lady and understands these risks, has limited banks exposure to 4%, but Treasury Secretary Paulson and the banks want higher limits for "increased liquidity." If we have learned nothing else in the past three years, "increased liquidity" is nothing more than code words for indiscriminate loans to increase short-term corporate profits, to heck with what happens to those loans in the future.
Paul
In short, banks issue mortgage back bonds to finance real estate loan purchases. The loans remain on the banks' balance sheets, thus, if the bank fails, the loans are repaid to the investors ahead of payments to the FDIC. If there are insufficient assets to repay the FDIC, the FDIC takes another financial hit. Enough financial hits to the FDIC, and we are back to the taxpayer paid S&L bailout of 1990. FDIC Sheila Bair, who is a very bright lady and understands these risks, has limited banks exposure to 4%, but Treasury Secretary Paulson and the banks want higher limits for "increased liquidity." If we have learned nothing else in the past three years, "increased liquidity" is nothing more than code words for indiscriminate loans to increase short-term corporate profits, to heck with what happens to those loans in the future.
Paul
Thursday, July 31, 2008
My Prediction, Part II
Okay, not really a prediction, but it seemed to tie to yesterday's post.
I use Radarlogic to monitor local price trends. Not perfect, but it allows me to compare prices over time. For example, current (May 31, 2008, because Radarlogic lags 60 days) Sacramento MSA price is the same as March 2003.
Again, I don't know where prices are going to go, but I feel comfortable in predicting a minimum 10% additional decline (and possible additional 20% decline, all on a local level, of course). A 10% decline, per Radarlogic, would take us back to May 2002 home prices. A 20% decline would take us back to May 2001 prices.
If we see 20% further local declines (which I am not predicting but could happen), that would mean that everyone who bought after March 2003, even with 20% down, would have negative equity. Pretty discouraging numbers, but certainly motivation to be a patient renter.
I use Radarlogic to monitor local price trends. Not perfect, but it allows me to compare prices over time. For example, current (May 31, 2008, because Radarlogic lags 60 days) Sacramento MSA price is the same as March 2003.
Again, I don't know where prices are going to go, but I feel comfortable in predicting a minimum 10% additional decline (and possible additional 20% decline, all on a local level, of course). A 10% decline, per Radarlogic, would take us back to May 2002 home prices. A 20% decline would take us back to May 2001 prices.
If we see 20% further local declines (which I am not predicting but could happen), that would mean that everyone who bought after March 2003, even with 20% down, would have negative equity. Pretty discouraging numbers, but certainly motivation to be a patient renter.
Wednesday, July 30, 2008
My prediction
I don't profess to know what is going to happen 5 minutes from now, let alone next week, next month or next year. But that doesn't stop me from having beliefs that only time will tell are right or wrong.
Tomorrow is the last day of July. I think a lot of sellers have been holding off dropping prices over the summer, hoping to find a buyer who is participating in the claimed summer buying binge. Now that we are about to enter the month of August, I think we will start to see a small amount of capitulation and many of those sellers (read: banks) will make significant price reductions to try to capture a buyer before the market goes into the autumn/winter doldrums.
What is your prediction?
Paul
Tomorrow is the last day of July. I think a lot of sellers have been holding off dropping prices over the summer, hoping to find a buyer who is participating in the claimed summer buying binge. Now that we are about to enter the month of August, I think we will start to see a small amount of capitulation and many of those sellers (read: banks) will make significant price reductions to try to capture a buyer before the market goes into the autumn/winter doldrums.
What is your prediction?
Paul
Tuesday, July 29, 2008
More than a little irony
As you have no doubt heard by now, last night Merrill Lynch sold +$30 billion in mortgage backed securities for $.22 on the dollar. Personally, I think this is a big deal for several reasons. First, it forces other CDO holders to mark their securities down to $.22 on the dollar (read: More write downs to come). Second, I am guessing this is close to the floor for markdowns on CDOs, after all, how much lower can the price go after a 22% mark down?
But what I find interesting is that Merrill sold the approximate $6.7 billion in CDOs, to a buyer who paid only 25% down with Merrill financing the balance. Now admittedly this is better than the 100% home financing that got Merrill into this situation, but the 100% home financing was in a rising home price market, whereas the 75% financing of the CDO's are in a declining CDO price market (Merrill valued these CDO's at +$11 billion only 28 days ago). So will Merrill soon be foreclosing on the CDO's that it just sold, while the CDO's are foreclosing on the underlying homes?
Paul
But what I find interesting is that Merrill sold the approximate $6.7 billion in CDOs, to a buyer who paid only 25% down with Merrill financing the balance. Now admittedly this is better than the 100% home financing that got Merrill into this situation, but the 100% home financing was in a rising home price market, whereas the 75% financing of the CDO's are in a declining CDO price market (Merrill valued these CDO's at +$11 billion only 28 days ago). So will Merrill soon be foreclosing on the CDO's that it just sold, while the CDO's are foreclosing on the underlying homes?
Paul
Sunday, July 27, 2008
The "stealth" bailout
You all know about the $300 billion "Stick it to your Children Act of 2008," but have you done the math for the rest of the bailout (so far)?
From CNBC:
1. Gone (in the past 12 months) from the Fed's balance sheet, $311 b in treasuries, used for such things as auction rate securities to Wall Street banks, bailout of Bear Stearns, etc.
2. Federal Home Loan bank "advances" to members using members' mortgage securities as "collateral," $284 b.
3. Mortgage securities purchased by Fannie/Freddie in the past 12 months, or so, $621 b.
4. Added to FHA (unrelated to the legislation passed this week), $90 b.
Total per CNBC, $1.43 trillion. (I know, my numbers don't add up. If you read the original CNBC article, you will see why my numbers are actually less.
Maybe all of these billions will be repaid. Maybe not. As someone in my office opined, we need to make more children to help pay these future debts off!
Paul
From CNBC:
1. Gone (in the past 12 months) from the Fed's balance sheet, $311 b in treasuries, used for such things as auction rate securities to Wall Street banks, bailout of Bear Stearns, etc.
2. Federal Home Loan bank "advances" to members using members' mortgage securities as "collateral," $284 b.
3. Mortgage securities purchased by Fannie/Freddie in the past 12 months, or so, $621 b.
4. Added to FHA (unrelated to the legislation passed this week), $90 b.
Total per CNBC, $1.43 trillion. (I know, my numbers don't add up. If you read the original CNBC article, you will see why my numbers are actually less.
Maybe all of these billions will be repaid. Maybe not. As someone in my office opined, we need to make more children to help pay these future debts off!
Paul
Friday, July 25, 2008
Historical Housing Statistics along Highway 50 in Sacramento
As I mentioned yesterday, I'm a little burnt out on our home search and depressed about our prospects for finding a home anytime soon......
So instead I am generating some data to keep idle Friday workers entertained. Below is the monthly DataQuick sales count, median price per square foot, and median sales price data I have collected from the SacBee website for the major zips along Hwy 50 in Sacramento (95819, 95826, 95827, 95670, 95630). As with all my SacBee DQ data, I don't have any means of updating it (like when DQ changed their methodology), so for the record I am not making any representations as to the data's accuracy.
Feel free to post Zip requests. I will try and fill them next week.


So instead I am generating some data to keep idle Friday workers entertained. Below is the monthly DataQuick sales count, median price per square foot, and median sales price data I have collected from the SacBee website for the major zips along Hwy 50 in Sacramento (95819, 95826, 95827, 95670, 95630). As with all my SacBee DQ data, I don't have any means of updating it (like when DQ changed their methodology), so for the record I am not making any representations as to the data's accuracy.
Feel free to post Zip requests. I will try and fill them next week.


Thursday, July 24, 2008
Seven Cent Solicitation
I just don't have much to say lately and am on on a deadline...so feel free to post RE related thoughts.
I would be especially keen to hear everyone's seven cents on the recent Housing Legislation passed by Congress. My hope for a veto was recently extinguished.
At least there are some provisions for first time buyers...but they look a bit complicated at first blush (and could anyone figure out the definition of a first time buyer...it tends to vary by context?).
I will try and post some historical data on different Sacramento zips in the coming days to fill some space.
(Why not two cents? According to Webster's "two cents" tends to be unwelcome/unsolicited advise, so I figure I'm inviting comments, coupled with inflation, and a bit of tongue twister....and voila.....seven cents.)
I would be especially keen to hear everyone's seven cents on the recent Housing Legislation passed by Congress. My hope for a veto was recently extinguished.
At least there are some provisions for first time buyers...but they look a bit complicated at first blush (and could anyone figure out the definition of a first time buyer...it tends to vary by context?).
I will try and post some historical data on different Sacramento zips in the coming days to fill some space.
(Why not two cents? According to Webster's "two cents" tends to be unwelcome/unsolicited advise, so I figure I'm inviting comments, coupled with inflation, and a bit of tongue twister....and voila.....seven cents.)
Wednesday, July 23, 2008
The Power of Averages
Some may be familiar with the anecdote of when Sir Francis Galton visited a livestock fair in 1906. While there, he stumbled onto a contest where villagers were to guess the weight of an ox. He found that if he took the average of all the guesses, it came within one pound, even though no one's guess was correct.
All this to say, I am a little disappointed that the average of all the experts didn't quite work out in this situation. I am continually stunned by the fact that so many "experts" were blindsided by the housing and mortgage bubbles.
If you ask me, most were clueless because they were so out of touch with average Americans. If you are working 80 hours a week, and only hang out with like minded individuals (often from the same profession), you have no way of knowing the struggles average people face. As I stated in an earlier post, Wall Street does not know the lives behind the Main Street data. The data can only tell you so much. When things were good, no one felt the need to look beyond the data.
This is where I have always had the upper hand. I'm the type of person who will start chatting you up in line at the supermarket to pass the time. I was also that person in high school who refused to stick with one particular group of friends (the jocks, the ags, the surfers, the goths etc). I have family all over the state in many lines of work (some blue collar, some white collar) and I love to listen to people's stories (which is ironic since I tell mine on a daily basis).
So yes, I have a masters and can analyze data, but I also read columns from various new sources (not just gloom and doom blogs), and listen to what average people have to say. Of course I sometimes get worked up reading the housing bubble blogs, but I try hard to keep an open and objective frame of mind.
All this to say, I am a little disappointed that the average of all the experts didn't quite work out in this situation. I am continually stunned by the fact that so many "experts" were blindsided by the housing and mortgage bubbles.
If you ask me, most were clueless because they were so out of touch with average Americans. If you are working 80 hours a week, and only hang out with like minded individuals (often from the same profession), you have no way of knowing the struggles average people face. As I stated in an earlier post, Wall Street does not know the lives behind the Main Street data. The data can only tell you so much. When things were good, no one felt the need to look beyond the data.
This is where I have always had the upper hand. I'm the type of person who will start chatting you up in line at the supermarket to pass the time. I was also that person in high school who refused to stick with one particular group of friends (the jocks, the ags, the surfers, the goths etc). I have family all over the state in many lines of work (some blue collar, some white collar) and I love to listen to people's stories (which is ironic since I tell mine on a daily basis).
So yes, I have a masters and can analyze data, but I also read columns from various new sources (not just gloom and doom blogs), and listen to what average people have to say. Of course I sometimes get worked up reading the housing bubble blogs, but I try hard to keep an open and objective frame of mind.
Tuesday, July 22, 2008
Did you ever have that feeling?
I have toured houses that were for sale, and my skin crawled because they were so dirty. I have toured houses where I knew a death had occurred, with no particular reaction other than sadness over the loss of life. When I have listened to others tell me about their "dark feelings" in a particular house, I have tended to be cynical and mostly polite, thinking of a house as a commodity and shelter, free from the evil forces that Hollywood movies conjure. This all changed when I walked into an otherwise unremarkable home on Sunday afternoon. I do not believe I have ever in my life felt such a dark and deathly force overcome me. I don't know anything about that home's history, but I was shocked at both the existence of the feeling and the overwhelming magnitude of the feeling. I immediately grabbed Mrs. Paul and almost ran from the house, not explaining the "why" to her until we were safely in the car.
Maybe I've turned into a "kook" after all?
Maybe I've turned into a "kook" after all?
Monday, July 21, 2008
Folsom & El Dorado Hills Historical Home Sales Data - June 2008 Update
Below are the latest sales and $$ charts for Folsom and El Dorado Hills. The downward pricing trend is continuing. We are now at $183 median price per square foot in EDH! Not nearly as promising in Folsom, which stands at $206 as of June. Hence we have just about stopped looking in Folsom, since we can get much more house for the $$ in EDH.
Sales in both zips seem to be leveling off a bit, which is why the year-over-year numbers look so promising. One of the main reasons I look at the data over a longer time horizon is because y-o-y numbers can be very misleading. Comparing a bad year to another bad year, doesn't give enough context for the data.
Anecdotal note: Was out for my usual walk with the kids yesterday afternoon, and saw a piece of paper taped to the door of a house we always pass. I didn't go up to check, but I have a strong feeling it wasn't a cookie recipe from a neighbor. This home wasn't even in my www.foreclosureradar.com data. With the HOA maintaining the outside of homes in Serrano, there isn't much to outwardly indicate financial stress. So its always a bit of a shock for me, as opposed to a predictable progression.


Sales in both zips seem to be leveling off a bit, which is why the year-over-year numbers look so promising. One of the main reasons I look at the data over a longer time horizon is because y-o-y numbers can be very misleading. Comparing a bad year to another bad year, doesn't give enough context for the data.
Anecdotal note: Was out for my usual walk with the kids yesterday afternoon, and saw a piece of paper taped to the door of a house we always pass. I didn't go up to check, but I have a strong feeling it wasn't a cookie recipe from a neighbor. This home wasn't even in my www.foreclosureradar.com data. With the HOA maintaining the outside of homes in Serrano, there isn't much to outwardly indicate financial stress. So its always a bit of a shock for me, as opposed to a predictable progression.


Sunday, July 20, 2008
Mistaken Identity
I wake up Saturday morning and check my e-mail. A great home in one of our favorite neighborhoods had dropped it's price 75k! Boy was I excited. It was in our price range, even with current interest rates.
I was very hopeful (an actual owner occupied home), but wanted to move quickly since homes in the lower price range are selling much more briskly around here. We even took my MIL by the house, since she was in town for the night.
To make a long story short.....turns out, the agent put the price on the wrong house (even though the wrong price equated to the average price per square foot for EDH last month).
Needless to say, I was crushed.
I was very hopeful (an actual owner occupied home), but wanted to move quickly since homes in the lower price range are selling much more briskly around here. We even took my MIL by the house, since she was in town for the night.
To make a long story short.....turns out, the agent put the price on the wrong house (even though the wrong price equated to the average price per square foot for EDH last month).
Needless to say, I was crushed.
Friday, July 18, 2008
Bankruptcy anyone?
From foreclosure.com:
The last bankruptcy in El Dorado County was filed in August 2007 ... that is until June 2008. In June and the first two weeks in July 2008, there have already been 40 bankruptcy filings. (Filings actually take place in Federal court in Sacramento, but the debtor addresses are listed in EDC.) No area is immune, including 12 in EDH, several in the high rent portion of Cameron Park, and a couple in South Lake Tahoe.
The last bankruptcy in El Dorado County was filed in August 2007 ... that is until June 2008. In June and the first two weeks in July 2008, there have already been 40 bankruptcy filings. (Filings actually take place in Federal court in Sacramento, but the debtor addresses are listed in EDC.) No area is immune, including 12 in EDH, several in the high rent portion of Cameron Park, and a couple in South Lake Tahoe.
June/July 2008 Month's Inventory
Month's inventory for the zips I track has dipped even more this month, down to 4.2 from 4.5. It's amazing what happens when homes start to become affordable again!
I haven't seen as many rentals on the market lately either (at least where I live). So I am beginning to wonder if low supply will put upward pressure on rents, which will further facilitate market normalization (rents go up, and home prices go down...eventually finding an equilibrium point between the two adjustments).
Of course the elephant in the room is distressed inventory......which should continue to hit the market now that the Alt-A and Option ARM is starting to implode. I have started skimming Mr. Mortgage's blog. He has some disturbing predictions for what's to come.
Zips are sorted from high to low, month's inventory. Sales is from DataQuick courtesy of the SacBee, and inventory was collected for SFH resales from ZipRealty.

I haven't seen as many rentals on the market lately either (at least where I live). So I am beginning to wonder if low supply will put upward pressure on rents, which will further facilitate market normalization (rents go up, and home prices go down...eventually finding an equilibrium point between the two adjustments).
Of course the elephant in the room is distressed inventory......which should continue to hit the market now that the Alt-A and Option ARM is starting to implode. I have started skimming Mr. Mortgage's blog. He has some disturbing predictions for what's to come.
Zips are sorted from high to low, month's inventory. Sales is from DataQuick courtesy of the SacBee, and inventory was collected for SFH resales from ZipRealty.

Thursday, July 17, 2008
Too Shady to Sell
Some of you may remember an earlier post on a home near downtown Folsom, that was too good to be true. Well I guess they learned their lesson, and have now included the adjacent parcel and dropped their price even further. The new MLS listing number is 80062942.
Glad to see these shady sales tactics are not being rewarded by the market.
Glad to see these shady sales tactics are not being rewarded by the market.
Deer in the Headlights
I am off the grid for a mere 5 days (our annual Yosemite trip), and I come back to find our nation's financial system teetering on the precipice.
Coming back to all the news reports, which I still haven't quite sifted though, my general mood about the future has gone from nervous trepidation, to helpless and overwhelmed angst.
Let me start by saying, we are a very average American family. We don't have an army (of accountants, financial advisers, lawyers, tax preparers etc.) at our beck an call to offer advise and expertise. We also come from working class families, so we really don't have any trusted relatives we can turn to for this type of advise.
While my gut has been telling me we were headed for rocky economic times, I have been at a loss as to what actions to take in response. The vast majority of our savings is in 401k (except our down payment). Back in January I attempted to read up on my 401k investment options to look for a safer choice going forward. But with all the disclaimers they put in, its really hard to tell what the true risk is for each fund....even the money market and cash reserves seem to have large disclaimers about no guarantee on your principle. Needless to say, I didn't get very far, and gave up. In hindsight, I would have been much better served to have found some help on this.
At this point I am a bit like a deer in the headlights. To preserve the purchasing power of our down payment, I feel we should buy a home soon, as a hedge against inflation and higher interest rates. But at the same time I don't want to purchase a depreciating asset, which is also a quick way to lose our down payment.
I have developed this nagging feeling that I need to be doing something to prepare ourselves financially and physically for hard times ahead, yet I am at a loss as to what exactly those preparations should be.
I am also starting to wonder if I would be better off in ignorant bliss. I would love to know what others have done in response (to the future prospects of our changing economy), if anything.
Coming back to all the news reports, which I still haven't quite sifted though, my general mood about the future has gone from nervous trepidation, to helpless and overwhelmed angst.
Let me start by saying, we are a very average American family. We don't have an army (of accountants, financial advisers, lawyers, tax preparers etc.) at our beck an call to offer advise and expertise. We also come from working class families, so we really don't have any trusted relatives we can turn to for this type of advise.
While my gut has been telling me we were headed for rocky economic times, I have been at a loss as to what actions to take in response. The vast majority of our savings is in 401k (except our down payment). Back in January I attempted to read up on my 401k investment options to look for a safer choice going forward. But with all the disclaimers they put in, its really hard to tell what the true risk is for each fund....even the money market and cash reserves seem to have large disclaimers about no guarantee on your principle. Needless to say, I didn't get very far, and gave up. In hindsight, I would have been much better served to have found some help on this.
At this point I am a bit like a deer in the headlights. To preserve the purchasing power of our down payment, I feel we should buy a home soon, as a hedge against inflation and higher interest rates. But at the same time I don't want to purchase a depreciating asset, which is also a quick way to lose our down payment.
I have developed this nagging feeling that I need to be doing something to prepare ourselves financially and physically for hard times ahead, yet I am at a loss as to what exactly those preparations should be.
I am also starting to wonder if I would be better off in ignorant bliss. I would love to know what others have done in response (to the future prospects of our changing economy), if anything.
Wednesday, July 16, 2008
More signs of the times
We live in a geographically isolated part of Cameron Park, in an area with about 70 newer homes.
In early 2005, if a home listed, it went pending within 24 hours. By autumn 2005, there were 18 homes for sale, of which 14 were vacant.
Now, there are 9 homes for sale, 2 vacant. Four homes are in some stage of foreclosure.
One neighbor used to have magnetic signs on their cars advertising his/her mortgage company. The signs disappeared some time back, and yesterday, so did the neighbor, driving away behind two big moving company vans. The loan has been in default since May 2008 but the house hasn't been listed and like most REO's that I see, no one even attempted to sell it before they let it go back to the bank.
In early 2005, if a home listed, it went pending within 24 hours. By autumn 2005, there were 18 homes for sale, of which 14 were vacant.
Now, there are 9 homes for sale, 2 vacant. Four homes are in some stage of foreclosure.
One neighbor used to have magnetic signs on their cars advertising his/her mortgage company. The signs disappeared some time back, and yesterday, so did the neighbor, driving away behind two big moving company vans. The loan has been in default since May 2008 but the house hasn't been listed and like most REO's that I see, no one even attempted to sell it before they let it go back to the bank.
Tuesday, July 15, 2008
Today's WSJ ...
Sorry I'm a little short on time today, but some odds and ends from this morning's WSJ:
1. One of the new requirements that Bernanke is imposing on mortgage lenders, is the novel idea of requiring that the mortgage lender actually take steps to verify that a borrower can repay the loan. I wonder if certain members of Congress are going to be as outraged over this proposal as they have been over other recent events. Don't worry about a sudden dearth of homebuyers ... the new rules wouldn't take effect until October 1, 2009!
2. IndyMac has suspended home foreclosures, saying it (the FDIC) wants to help as many people as possible remain in their homes. As you will recall, IndyMac was at the forefront of the no-doc jumbo loan market. So now that you and I own IndyMac (or at least its liabilities via the FDIC), there are unlimited resources available to keep the folks in homes they perhaps couldn't afford in the first place.
3. Unrelated to the new Fed rules, lenders (including Fannie/Freddie) are now requiring borrowers to have an adequate downpayment, credit history and demonstrated ability to pay, or in the alternative, requiring borrowers to obtain mortgage insurance (from one of the likely insolvent mortgage insurers). At the same time, the mortgage insurers are scrutinizing the borrowers to make a similar inquiry into the borrowers ability to repay the loans. This will likely increase the cost of borrowing, reducing the amount folks can borrow, and reducing the pool of possible buyers for the mountain of inventory out there.
4. Another aspect of the Feds new requirements for mortgage lenders, is the return of the impound account for taxes and insurance.
Now if they would only enforce the thousands of rules and laws already on the books ... sigh.
Paul
1. One of the new requirements that Bernanke is imposing on mortgage lenders, is the novel idea of requiring that the mortgage lender actually take steps to verify that a borrower can repay the loan. I wonder if certain members of Congress are going to be as outraged over this proposal as they have been over other recent events. Don't worry about a sudden dearth of homebuyers ... the new rules wouldn't take effect until October 1, 2009!
2. IndyMac has suspended home foreclosures, saying it (the FDIC) wants to help as many people as possible remain in their homes. As you will recall, IndyMac was at the forefront of the no-doc jumbo loan market. So now that you and I own IndyMac (or at least its liabilities via the FDIC), there are unlimited resources available to keep the folks in homes they perhaps couldn't afford in the first place.
3. Unrelated to the new Fed rules, lenders (including Fannie/Freddie) are now requiring borrowers to have an adequate downpayment, credit history and demonstrated ability to pay, or in the alternative, requiring borrowers to obtain mortgage insurance (from one of the likely insolvent mortgage insurers). At the same time, the mortgage insurers are scrutinizing the borrowers to make a similar inquiry into the borrowers ability to repay the loans. This will likely increase the cost of borrowing, reducing the amount folks can borrow, and reducing the pool of possible buyers for the mountain of inventory out there.
4. Another aspect of the Feds new requirements for mortgage lenders, is the return of the impound account for taxes and insurance.
Now if they would only enforce the thousands of rules and laws already on the books ... sigh.
Paul
Sunday, July 13, 2008
Fannie and Freddie
As you know, Fannie and Freddie's status is currently in question (notwithstanding efforts to prop them up). Briefly, they hold or have insured about $5 trillion (yes, trillion) in mortgages. Combined, their capital is a little more than $50 billion. And about 1% of their loans are currently delinquent (about $50 billion). If their portfolio's don't get any worse (highly unlikely IMO), their capital is already at risk of being erased.
As you also know, our gubmint is working on homeowner "rescue" legislation that would, among other things, permanently increased the Fannie and Freddie loan limits from $417k to $729,750. So if Fannie and Freddie are soon to be (if not already) insolvent, what impact will doubling the loan limits have on them?
And if you haven't read the fine print in the legislation regarding the tax credit for new home buyers, according to the WSJ, the buyer must repay that tax credit over 15 years. In other words, an unsecured, no interest, mortgage on top of a mortgage. As if that isn't what is getting so many people in trouble now!
Paul
As you also know, our gubmint is working on homeowner "rescue" legislation that would, among other things, permanently increased the Fannie and Freddie loan limits from $417k to $729,750. So if Fannie and Freddie are soon to be (if not already) insolvent, what impact will doubling the loan limits have on them?
And if you haven't read the fine print in the legislation regarding the tax credit for new home buyers, according to the WSJ, the buyer must repay that tax credit over 15 years. In other words, an unsecured, no interest, mortgage on top of a mortgage. As if that isn't what is getting so many people in trouble now!
Paul
Friday, July 11, 2008
July 2008 Inventory by Zip
This is the first month that I have comparable year over year inventory data (from ZipRealty). Looks like we are almost 16% below last year at this point, but we are also 7.7% above last month. So this means sales have slowed or listings have picked up, or a bit of both.
I sorted the zips by % change over last year. As you can see, the relatively expensive zips where prices haven't fallen as much are lagging behind. Their inventory is still growing.

I sorted the zips by % change over last year. As you can see, the relatively expensive zips where prices haven't fallen as much are lagging behind. Their inventory is still growing.

At Any Rate?
The Bee had a story last week that hit close to home. All three of the homes we have tried to purchase, led to negotiations with the bank (2 REOs, 1 SS). In two of the three cases, negotiations played out over months, as opposed to days.
In both of those cases , I watched interest rates fluctuate over the course of our drawn out negotiations. This gave me considerable heartburn as I had predicated our offer on a particular rate (a tad conservative, but obviously not enough to capture the fairly large changes).
So of course, being the risk averse planner that I am, I wanted a rate lock. So here comes the Catch-22. To get a rate lock, I need a contract, but to agree on a contract price, I wanted a rate lock. Argh.
As of today, both of the REOs are Pending, and the SS is still sitting.
In both of those cases , I watched interest rates fluctuate over the course of our drawn out negotiations. This gave me considerable heartburn as I had predicated our offer on a particular rate (a tad conservative, but obviously not enough to capture the fairly large changes).
So of course, being the risk averse planner that I am, I wanted a rate lock. So here comes the Catch-22. To get a rate lock, I need a contract, but to agree on a contract price, I wanted a rate lock. Argh.
As of today, both of the REOs are Pending, and the SS is still sitting.
Thursday, July 10, 2008
Seed Money Update
Given all the gardening interest from the Government Seed Money post, I thought I would offer a quick update on our little container garden.
Keep in mind, my kids helped with the planting. My 4 year old was very meticulous about getting the seeds in the holes, but my 2 year old flung them about the minute they hit his hand. All this to say, the labels may not match the sprouts. We over seeded, and will have to thin some of the sprouts. I haven't done this in a while, and figured our odds were better if there were more seeds.
Thyme - very small with little growth since they broke ground
Rosemary - nothing
Basil - seems every seed has sprouted and they are over an inch tall now.
Sage - nothing
Pepper - a couple small sprouts
Marjoram - nothing
Cilantro - lots of good sizes sprouts
Parsley - can't tell if they are parsley sprouts (which I imagine look a lot like cilantro) or if they are just wayward cilantro sprouts.
I think the Pepper and Marjoram may have drowned, my kids "helped" water that bucket when I wasn't paying attention. My 4 year old is spellbound by the whole process, and gives us daily progress reports.
Keep in mind, my kids helped with the planting. My 4 year old was very meticulous about getting the seeds in the holes, but my 2 year old flung them about the minute they hit his hand. All this to say, the labels may not match the sprouts. We over seeded, and will have to thin some of the sprouts. I haven't done this in a while, and figured our odds were better if there were more seeds.
Thyme - very small with little growth since they broke ground
Rosemary - nothing
Basil - seems every seed has sprouted and they are over an inch tall now.
Sage - nothing
Pepper - a couple small sprouts
Marjoram - nothing
Cilantro - lots of good sizes sprouts
Parsley - can't tell if they are parsley sprouts (which I imagine look a lot like cilantro) or if they are just wayward cilantro sprouts.
I think the Pepper and Marjoram may have drowned, my kids "helped" water that bucket when I wasn't paying attention. My 4 year old is spellbound by the whole process, and gives us daily progress reports.
Indicator of Things to Come
Every time I look at the latest market stress stats, the first word that comes out of my mouth is, "wow." I am still pretty floored at how rapidly both these zips are deteriorating. I think my earlier predictions, of another 10% drop, may have been too tame. Gas at $4.50 a gallon surely isn't helping.
I should also note that EDH's inventory is a bit misleading (tall green bar), while it looks high relative to Folsom, a third of the inventory is homes over $800,000. They are selling at a very very slow pace. I think there were 8 pending out of 150 homes when I last checked. Can you imagine the carrying cost on those for two years...yikes!

I should also note that EDH's inventory is a bit misleading (tall green bar), while it looks high relative to Folsom, a third of the inventory is homes over $800,000. They are selling at a very very slow pace. I think there were 8 pending out of 150 homes when I last checked. Can you imagine the carrying cost on those for two years...yikes!

Wednesday, July 9, 2008
The Mommy Connection
Several months ago, I received an e-mail from a mom whom I had met at Bunco shortly after I moved here. She asked if I had anything to do with a local RE blog........doh! She obviously has an above average memory.
Well since that time, we have started meeting for play dates regularly. Aside from all the usual kiddy talk, we share a lot of dirt on housing related stories. She has been a great source, especially since she has lived here longer and knows her neighbors much better than we do.
So on to her latest dish......
Apparently someone in her neighborhood, struggling to avoid foreclosure, moved out at 3am.
I have heard reports of this in the news/blogs, but have never quite understood it. Why in the middle of the night? Did they take all the appliances and didn't want anyone to witness? If that is the point, wouldn't they do it in the middle of the work week when everyone is gone? I would think nighttime would be when all the neighbors would wake up and want to know what the heck was going on. Or perhaps, moving vans are in such high demand that 3am is the only time they have available? In any case, the situation strikes me as very odd.
A friend of hers who lives nearby, in the RE industry, had regularly refied their home. She was so underwater, that their monthly payment was almost twice our rent, even though their home was considerably smaller. Their home is now in foreclosure. Too much Kool-Aid. Now I am a big fan of personal responsibility and living within your means, but in some cases, like this one, it doesn't make sense for a person to try and stay. Walking away, renting for seven years, seems like a much better alternative to complete financial suicide.
The bank did not have to give them the money. The bank also set the terms for the contract that they signed, which lays out all remedies if they cannot pay. I don't understand why some feel it is such a bad thing to walk in this situation (I was raked over the coals by another blog for my thoughts on this...by a lawyer of all people....whom you would think would understand the idea of a contract).
Of course if there is any type of fraud or misrepresentation involved, that is another ball of wax entirely.
____________
Six months ago, I heard of these types of stories, but they occurred in places like Elk Grove and Natomas. Now they are in my neighborhood. Unfortunately, no zip code is immune.
Well since that time, we have started meeting for play dates regularly. Aside from all the usual kiddy talk, we share a lot of dirt on housing related stories. She has been a great source, especially since she has lived here longer and knows her neighbors much better than we do.
So on to her latest dish......
Apparently someone in her neighborhood, struggling to avoid foreclosure, moved out at 3am.
I have heard reports of this in the news/blogs, but have never quite understood it. Why in the middle of the night? Did they take all the appliances and didn't want anyone to witness? If that is the point, wouldn't they do it in the middle of the work week when everyone is gone? I would think nighttime would be when all the neighbors would wake up and want to know what the heck was going on. Or perhaps, moving vans are in such high demand that 3am is the only time they have available? In any case, the situation strikes me as very odd.
A friend of hers who lives nearby, in the RE industry, had regularly refied their home. She was so underwater, that their monthly payment was almost twice our rent, even though their home was considerably smaller. Their home is now in foreclosure. Too much Kool-Aid. Now I am a big fan of personal responsibility and living within your means, but in some cases, like this one, it doesn't make sense for a person to try and stay. Walking away, renting for seven years, seems like a much better alternative to complete financial suicide.
The bank did not have to give them the money. The bank also set the terms for the contract that they signed, which lays out all remedies if they cannot pay. I don't understand why some feel it is such a bad thing to walk in this situation (I was raked over the coals by another blog for my thoughts on this...by a lawyer of all people....whom you would think would understand the idea of a contract).
Of course if there is any type of fraud or misrepresentation involved, that is another ball of wax entirely.
____________
Six months ago, I heard of these types of stories, but they occurred in places like Elk Grove and Natomas. Now they are in my neighborhood. Unfortunately, no zip code is immune.
Tuesday, July 8, 2008
A Few of My Favorite Things
Two years ago this week, I saw perhaps the most remarkable home in the entire United States, Falling Water. It is a stunning piece of architecture, and a magnificent engineering feat for its day, but not exactly a home I would want to live in.
This got me thinking about the architectural elements that make a home suitable for everyday life, as well as the flourishes and design elements I am drawn to.....here are a couple of my favorite things (although they don't all necessarily belong in the same house.....
Design Elements
In general I love the rustic farmhouse look, which includes, exposed wood beams, lots of covered porches and balconies, pine or other rustic wood cabinetry (the type they are always covering over or demolishing in HGTV specials....much to my chagrin). I don't really like tile, but will make an exception for slate. I also like darker metals and woods, no polished brass or oak. I prefer homes with a nice open flow, no need for a separate dining or living room etc. We are not formal people.
Livability
Entry closet near the front door for shoes, jackets and umbrellas.
Laundry near the bedrooms.
Back patio access near the kitchen or main living area.
The bedrooms should be grouped together and somewhat separate from the main living area.
No carpet in the eating areas.
Closets should not have sliding doors so large that you can't easily access what is inside.
(I'm sure there is much much more to this list, but I have to get back to my day job)
If anyone happens to run across my perfect home in their MLS searches, do let me know.
This got me thinking about the architectural elements that make a home suitable for everyday life, as well as the flourishes and design elements I am drawn to.....here are a couple of my favorite things (although they don't all necessarily belong in the same house.....
Design Elements
In general I love the rustic farmhouse look, which includes, exposed wood beams, lots of covered porches and balconies, pine or other rustic wood cabinetry (the type they are always covering over or demolishing in HGTV specials....much to my chagrin). I don't really like tile, but will make an exception for slate. I also like darker metals and woods, no polished brass or oak. I prefer homes with a nice open flow, no need for a separate dining or living room etc. We are not formal people.
Livability
Entry closet near the front door for shoes, jackets and umbrellas.
Laundry near the bedrooms.
Back patio access near the kitchen or main living area.
The bedrooms should be grouped together and somewhat separate from the main living area.
No carpet in the eating areas.
Closets should not have sliding doors so large that you can't easily access what is inside.
(I'm sure there is much much more to this list, but I have to get back to my day job)
If anyone happens to run across my perfect home in their MLS searches, do let me know.
Monday, July 7, 2008
One Subscription, Two Purposes
I was a little skeptical a couple weeks back when looking at the big spike in foreclosures and NODs in the surrounding neighborhoods. I was using the free search from www.foreclosure.com and thought some listings might be duplicates (but you have to pay the $$ to really know). So I signed up for the three day trial at www.foreclosureradar.com based on Mr.Mortgage's recommendation.
While the data was slightly different, the results were more or less the same. Best I could tell, neither service had complete and up to date info, without duplicates. All three foreclosure information services that I know of, charge about $50 a month for a subscription, which is pretty steep for an non-investor/home buyer (gratefully I found someone to help subsidize my subscription). www.realtytrac.com kinda pissed me off cause they won't tell you how much their service costs unless you put in all kinds of personal information first, so I didn't even bother considering them.
I plan to sign up this week, for two reasons. First and foremost, to make sure my landlord is paying the mortgage (I see it as a small insurance policy). And second, to get better information on the NODs and foreclosures prior to them hitting the MLS.
Anyone have a recommendation for a better foreclosure info site before I sign up with www.foreclosureradar.com?
While the data was slightly different, the results were more or less the same. Best I could tell, neither service had complete and up to date info, without duplicates. All three foreclosure information services that I know of, charge about $50 a month for a subscription, which is pretty steep for an non-investor/home buyer (gratefully I found someone to help subsidize my subscription). www.realtytrac.com kinda pissed me off cause they won't tell you how much their service costs unless you put in all kinds of personal information first, so I didn't even bother considering them.
I plan to sign up this week, for two reasons. First and foremost, to make sure my landlord is paying the mortgage (I see it as a small insurance policy). And second, to get better information on the NODs and foreclosures prior to them hitting the MLS.
Anyone have a recommendation for a better foreclosure info site before I sign up with www.foreclosureradar.com?
Subscribe to:
Posts (Atom)

 Posts

