Soon, it starts to add up.
So, how does everyone feel being the proud owner of AIG? Personally, I don't feel any better about it than the $200 billion I (as a taxpayer) paid for Fannie and Freddie, but sadly, the gub-mint doesn't care much about how we feel.
Paul
Tuesday, September 16, 2008


Monday, September 15, 2008
And then there were two......
Only two left.....with Lehman filing for bankruptcy, and Merrill being acquired by BofA. And of course Bear Sterns was acquired by JP Morgan in the Spring.
I feel bad saying this but I am experiencing a serious bout of schadenfreude. I realize many people at these firms had nothing to do with getting us into the current meltdown (i.e. the admin staff). But I can't help but feel that these firms and their employees were among the primary enablers. These folks with their MBAs and Ivy League degrees were supposed to "know better." They were supposed to correctly evaluate the risk and determine the appropriate actions. All the while, they were making ridiculous sums of money (as all on Wall Street do, regardless of their competency).
I have many friends and family suffering various consequences of the housing meltdown (most all in unrelated industries). In my mind, it only seems appropriate that Wall Street should also feel the consequences of its failings (beyond a reduction in their 6 figure annual bonus).
Sunday, September 14, 2008
September 2008 Sacramento Housing Inventory by Zip Code
Inventory is down both month-over-month and year-over-year. Compared to last year, there is 25% less single family home inventory on the market. Compared to last month, inventory is down around 3.5%.
One interesting exception of note, inventory in Midtown, Arden, Loomis and East Sac are up a bit over last year.

Inventory was gathered from ZipRealty for single family homes.
One interesting exception of note, inventory in Midtown, Arden, Loomis and East Sac are up a bit over last year.

Inventory was gathered from ZipRealty for single family homes.
Saturday, September 13, 2008
Hank Paulson needs a mistress
Don't get me wrong, I'm not normally an advocate of extra-marital affairs for anyone, but I've learned that when Hank Paulson works on the weekend, my share of the national debt goes up on a grand scale. Last weekend, he worked all weekend and the taxpayers (meaning you and me) promised to ante up $200 billion in fresh new capital for Fannie and Freddie. Now, Paulson's working this weekend on Lehman Brothers and that can only mean one thing for the taxpayer and its not good. So I'm thinking, maybe if Paulson had a mistress, he wouldn't have so much time on his hands to spend our money?
Paul
Paul
Friday, September 12, 2008
August foreclosure activity
From RealtyTrac, California was up 40% m-o-m in August, and up 75% y-o-y.
My "guess" that we might be on the cusp of a bottom, appears to have been premature with this much more REO inventory coming down the road.
But one AP writer possesses an overwhelmingly firm grasp of the obvious, stating, "If home prices and sales stabilize or improve, the foreclosure situation could get better."
Paul
Thursday, September 11, 2008
Stealing Minutes for Buying Time
Things are busy here. It's the end of our fiscal year, and I have also been traveling more than usual. Luckily Paul has been filling in.
We are also doing homework on a couple homes we are considering. More details to come.
I visited my Dad in Stockton last weekend at their new place. Haven't been down there in a long time. His wife suggested that the bars on the windows and around the front of the yard in the neighborhood are a decorative flair preferred by Hispanics.....I have to say I have never heard this before. But since they are the ones that have been living in Mexico, I wasn't about to contradict her. In any case, no shortage of vacant homes in the area.
Gotta run.....
2Q 2008 National Housing Metro Valuations
My favorite housing study was just updated for the 2Q 2008. While I really love the methodology used by the National City - Global Insight Housing Valuation Analysis I am starting to wonder if their statistical models have been skewed by the housing boom. As they now consider most of California to be fairly valued.
A small excerpt, "Extreme overvaluation is essentially nonexistent. Only six metro areas are judged to be overvalued during the second quarter of 2008, down from a peak of 51 metro areas in 2005. The decline of overvaluation is even greater when measured as a share of total housing units and real estate value."
A small excerpt, "Extreme overvaluation is essentially nonexistent. Only six metro areas are judged to be overvalued during the second quarter of 2008, down from a peak of 51 metro areas in 2005. The decline of overvaluation is even greater when measured as a share of total housing units and real estate value."
Tuesday, September 9, 2008
Above Average Unemployment
National unemployment is now over 6% .....but I don't think the whole story is being told. In my family alone, there has been considerable unemployment and underemployment in the last year an a half. This undermines the stability of young families and makes it difficult for them to save money.
Of my step-brothers & sisters, my brother, and my husbands brothers & sister (numbers include most spouses)....
4 were laid off within the last year and a half, but have found work. One was laid off and is still looking for work, and 9 are still employed. Another ships off to Iraq in a month, he couldn't find work so he rejoined the military. The one in jail doesn't count since he's not looking for work.
Of my extended family here in Sacramento, my aunt is still out of work, but Mr. BT's cousin found a new job that is better than his last one. My uncle, is being asked to take days without pay since they don't have much work (I consider this underemployment).
Have other families been impacted this much in recent years?
Monday, September 8, 2008
Answer: $51.75 per hour
Question: How much would you have had to earn each working hour this past year, to offset the loss in value if you owned a median priced home in Sacramento?
August 2007 median= $313,500
August 2008 median= $210,000
Loss = $103,500
Avg annual hours worked= 2,000
(If you prefer using "average" home price, rather than median, the answer would be $56.65/hour. If you prefer average price sq/ft, it would be about $60/hour assuming a 2,000 square foot home.)
Paul
Sunday, September 7, 2008
The national debt doubled this morning ...
So, the Feds have placed FNM and FRE into conservatorship, basically, adding their $5 trillion in loans (and loan guaranties) to the existing $5.7 trillion national debt. Yes, I know that is an oversimplification and that much of the loans will be repaid or collateral recovered so it won't be a $5 trillion loss (at least I hope not).
Two comments: First, expect FNE and FRE to freeze foreclosures of their portfolio loans. How else can they minimize the expected losses, if they keep adding REO inventory to an already depressed market? They will do this by letting the flippers and homeowners who are delinquent, keep the properties with "re-negotiated" loan terms, including reduced interest, principal and forgiven back payments.
Second, I don't usually rant about the mainstream media, but with 240 channels on my tv, only CSpan had the live coverage of Paulson's press conference. We double the national debt and it isn't maybe a little newsworthy? CNN carried the first 60 seconds of his 30 minute press conference, then the talking heads cut Paulson off to tell us their opinion of the impact of Treasury's actions, before Paulson had even finished! And CNBC decided its infomercial was more important.
And, yes, it's true, some say I need a life, but this is a huge event that I don't think most people understand or appreciate (except of course, the regular readers of Average Buyer).
Paul
Friday, September 5, 2008
Cha Ching!
Wholesale conforming interest rates just dipped below 6%!
I use the Mtg. Professor for the daily rate as well as some good info and advise.
I use the Mtg. Professor for the daily rate as well as some good info and advise.
Have you Been Waiting Long?
Working from a home office gets kinda lonely. So I try to get out as much as possible with the kids after work. I should also note that I am one of those folks who will strike up a conversation with just about anyone. (When I actually worked in the office, I was often the keeper of secrets when my coworkers needed to vent or sought advise.)
While at the pool in Folsom one afternoon this week I struck up a conversation with the mom sitting next to me. Turns out, they had moved into the area a year ago.....so of course I had to ask if they bought a home yet. They hadn't, and were also waiting!
It was like we had this instant bond, since we both felt a) everyone thought we were crazy by waiting and were tired of the "its a great time to buy" advise, and b) we were so happy to have someone to talk to since we can't really express our opinions with other parents who are homeowners (telling them we think prices will continue to deteriorate is not a good party topic).
It was a welcome relief for me to actually meet another family, just like ours, continuing to wait. Since almost everyone I know who wanted to buy a home has has now bought one in the last 6 months, I was starting to feel a bit like a hold out. My mom & her boyfriend, my dad & his wife, my babysitter, some parents we know from our kids school, several local bubble bloggers, even my real estate agent! (Of course the blog party back in April was great too, cause I got to meet other in the same situation as us.)
In any event, I may be alone at work, but I am not alone as I wait (even if it seems like it at times).
There is also a thread on the Sac Bee Blog today about someone who is waiting.
Thursday, September 4, 2008
Slightly Sunnier Outlook
There is a popular joke economists use to break the ice at the beginning of forecasting conferences.....
Q: Why did God create economists?
A: In order to make weather forecasters look good.
Just today I was making light of the recent IATA (International Air Transport Association) 2008 forecast. Which, just 9 months ago was 10.2 billion higher.
This got me to thinking about my own predictions over the last year.
Economy - Last year around this time, I was feeling increasingly queasy about the U.S. economy. I thought we would be in a full blown recession by now, as consumer spending slowed due to less and less HELOC $$ sloshing around. But banks and financials have been slow to respond to the new realities. Of course some will argue that we are in a recession, especially after today's unemployment numbers, but so far the economy has limped along.
Stock Market - I was rather shocked by the new high we hit back in October of last year. Why stocks were riding high (since they are supposed to be forward looking) mystified me. I was thinking we were in store for a 20% "correction" from the peak, which is not too far off from the current situation.
Interest Rates - I figured by fall, with high oil and commodity prices, inflation fears would prod the fed to increase rates. I guestimated that conforming mortgage rates would be around %6.75 by now, which was why I felt a bit pressured to purchase this spring. For a time they were close, but I am delighted to be wrong on this one.
Housing - I predicted that the bottom would hit for the lower end before it did for the higher end, and this seems to be playing out. I also predicted that the high end wouldn't fall as much as the low end, but it is still way too early to tell on that front.
So perhaps I have been overly bearish. Reading housing bubble blogs as a hobby can do that.
I leave you with another classic economist joke....
Three economists were on a hunting trip, and came across a large deer. The first economist fired, but missed, by a yard to the left. The second economist fired, but also missed, by a yard to the right. The third economist didn't fire, but instead shouted in triumph, "We got it! We got it!"
Wednesday, September 3, 2008
Stressed Out - 6 Month Update
Its now been exactly 6 months since I started collecting weekly foreclosure and preforeclosure stats from http://www.foreclosure.com/. I do not use a precise methodology, just a raw count of the number of active properties in 95762 & 95630 (the site has duplicates, and miss some listings but I feel the overall trends are indicative).

As you can see, the rate of increase in the NODs seems to be moderating a bit, especially for EDH. Since I began collecting statistics, EDH NODs are up 33% and foreclosures are up 262%. In Folsom, NODs are up 94% and foreclosures 215%.
Using a 3 month lag factor for the NODs to foreclosure, it looks like we are at a 30-40% "cure rate" (BTW my cure rate calculation is totally bogus since it doesn't track individual homes, just the ratio of NODs to foreclosures three months later).

Tuesday, September 2, 2008
The Weekly Screen Scrape
Of the homes that meet my purchase criteria in Folsom and El Dorado Hills area, the ratio of homes pending sale is at a record level, and has been increasing all month long. The under 500k market is where it's at.
Could this flurry of activity be due to the dip in interest rates? Or a rush to purchase while down payment assistance is still available. I'm not sure, but I have to admit, I was rather surprised by the recent numbers.
On the other hand, of the 150 or so homes listed in the MLS for sale in the EDH area over 750k, only 4 are pending sale. That's over 3 years of inventory (and that calculation makes the generous assumption that all three close this month).
Sunday, August 31, 2008
The Home Stretch
Of all the new home developments in the area, the one we are most tempted by is the Pulte Laurel Oaks development off Bass Lake Road in El Dorado Hills. They have single story homes, on nice sized lots, in a lovely little valley, and even managed to keep some of the existing oak trees.
Initially the prices were way too high and we had written them off our list. But they are close to finishing the development (which is a huge plus) and dropped their prices back in May to move the last couple homes, and added in some upgrades.
When we visited last time, we were incredibly tempted, but the lots weren't quite what we were looking for (odd slopes, angles etc). So it was a bit easier to pass up. At that time, there was a particular lot that I coveted, but it was already reserved. As with recent trends, the buyer pulled out....and now it's available.
When we sat down with the sales guy after looking at the home, the monthly quote he gave us was a bit surprising. It was considerably higher than we had calculated (his higher interest rate, my tax benefit inclusion). We could afford the payment, but it would really stretch us, and force us to change some of our spending/saving habits. It's also significantly higher than our current rent.
There are some not-so-minor financial issues. 20% on the home is a bit more than our current down payment, so we would have to get a loan from family to avoid PMI. Pulte won't pay our agents commission, which is really annoying, since I have been working with him for over a year to find a home. And, with all new homes, we would have to put in a backyard.
So basically, it all comes down to money, and how much we are willing to stretch. The home is everything we want, but money would be very tight in the short term. I'm just not sure the perfect home is worth the financial strain. Sigh.
Friday, August 29, 2008
Between a rock and a hard place
Lots of talk about the Feds doing something (what we don't know) with Fannie (FNM) and Freddie (FRE). With all of the uncertainty surrounding the survivability of FNM/FRE, it has driven their cost of money up, which in turn has increased the cost of mortgages, which in turn has reduced the number of qualified buyers/borrowers, which in turn leads to lower home prices, which in turn leads to more write-offs at banks, which .... Well, you get the picture.
FNM and FRE have $223b (yes, billion) in short term debts, maturing in September (starting next week). They need to pay this debt off, probably with new debt. But it remains to be seen whether they can borrow this much new money (and at what cost), with the uncertainty hanging over their heads.
The pundits say that if the government intervenes, the common stock will be wiped out. At $5/share, I think that is a done deal ... Even Bear Stearns shareholders got $10/share! But what about the next level of shareholder, the holders of preferred shares? In the pecking order, preferred shares are above common shareholders, but below debt holders. The $64,000 question is, would a Fed action wipe out the preferred shareholders (who are currently collecting dividend yields from FNM/FRE in the range of 16%)? Would the Feds wipe out the equity of $36b of preferred shareholders?
Now, before you all say "don't bailout the preferred shareholders," many of those shareholders are banks, and the preferred shares represent as much as 16-34% of some banks tangible capital (GBTS, MBHI, WABC). In the case of Sovereign Bancorp, we are talking about +$800m of FNM/FRE preferred stock on its books. So if the preferreds aren't bailed out, then it is likely the FDIC will be taking over more banks (another kind of taxpayer funded bailout), as the banks' balance sheets are devastated with the writeoff of their preferred FNM/FRE stock holdings.
Paul
Thursday, August 28, 2008
Auburn Update
MCB44 was kind enough to send some updated statistics for Auburn. They continue to show the trends we were seeing back in April; more sales at the lower end of the market. This mimics what we are seeing in many areas of Sacramento, and largely accounts for the huge drop in the median price being reported by DataQuick (since the bulk of the home that are actually selling are at the lower end of the spectrum).
This skewed distribution can be seen by contrasting the recent OFHEO figures with DQ median (which is showing between 20%-35% drop depending on the county). The OFHEO data only shows a 17.68% drop in prices over the last year, and are still showing a 22% increase over the last 5 years.
From the Bee's Homefront Blog, OFHEO "is the national gold standard for measuring home prices. It reflects the same homes sold over time rather than the median, which lately tends to reflect the lowest end of the market activity with foreclosure properties."
I don't know too many who's wages have increased 22% over the last 5 years (the equivalent of getting a 5% raise each year)*.....its no wonder the buyer's still can't keep up.

* Of course I work at a not-for-profit, so those in the private sector may have done better in the boom years.
Tuesday, August 26, 2008
The more things change, the more they stay the same
The Mortgage Asset Research Institute reports that the number of fraudulent mortgages climbed 42% in the first quarter of 2008, compared to the first quarter of 2007. The most common fraud is employment history and overstated income. The biggest jump came from understated liens and judgments. Florida leads with 24% of the nation's total, with California in second place (and 52% of those in Los Angeles).
Apparently, with mortgages harder to obtain, folks are being less candid on their loan apps. So will we see these loans coming back in a few years as REO's?
I found it interesting to read on the actual fraud report, MARI's tag line, "Know your customer." What a novel idea for a modern business.
Paul
Monday, August 25, 2008
Privatized profits and socialized losses
Seems like that is where America is headed now. Today's estimates are that Fannie/Freddie will require $200 billion in bailouts. Detroit automakers want another $50 billion in bailouts. I have previously summarized hundreds of billions in bailouts via the Federal Reserve, Federal Home Loan Banks, etc. And if history is a guide, the estimates are going to be way too low, and the actual bailouts will be much higher. After all, if $50 billion to Detroit doesn't work, the gubmint is in too deep to not give them more if they need it. Same thing with Fannie/Freddie. I guess equally important is the fact that once the gubmint starts bailing, it must keep bailing regardless of the cost, because if it stops, it would be tantamount to an admission that maybe it wasn't a great idea in the first place, and of course, a "waste" of all that money already spent on the bailout.
Those printing presses much be humming 24 hours a day printing new money for all of these "gifts" from Washington.
Paul
Those printing presses much be humming 24 hours a day printing new money for all of these "gifts" from Washington.
Paul
Sunday, August 24, 2008
The Credibility Gap
Yesterday on the flight to D.C. I was catching up on my WSJ reading. I was on August 6th and read the article on FirstFed. It was very unsettling, even though I had seen the accompanying graphics on Calculated Risk earlier in the month.
This got me to wonder, why does an issue have a larger impact on me when I am physically holding a paper with a chart of the data, as opposed to reading it on the internet?
I don't really know the answer, but imagine it has something to do with human nature. Often a problem becomes much more "real" when you or someone you know is directly affected by it.
Or could it be, that I had the time to sit and read every word of the article (as opposed to my usual skimming online) and absorb the true impact of what they were saying? Perhaps on the internet, there is just too much information vying for our attention. Which, in the end, results in nothing keeping our attention? To be fair, I was on deadline that week (hence the unread WSJ).
In any event, this is a pretty big deal (which many bubble bloggers already know about). In my immediate circle of friends and family I know of at least 3 folks with ARMs due to reset in the next two years. While many are calling bottom for the low end in Sacramento, I think the party is just getting started on the higher end.
Random note about queuing: At work I am surrounded by Operations Research folks, so queuing is very serious business. I use use LIFO when it comes to my reading stack. That way, all the articles anticipating an event don't need to get read, since I am reading how it was resolved before I even get to the earlier articles. As obsessive as I am about my WSJ reading and housing stats, I am actually a pretty laid back in most other respects.
Friday, August 22, 2008
Circling In
When we moved into our rental in the Fall of 2006, we signed a 6 month lease. We figured that would give us plenty of time to get reacquainted with the area and purchase a home. At the time, I was open to living in almost any family friendly part of Sacramento that had reasonable public schools.
Little did we know, we would still be renting the same home almost 2 years later. During this time, we have made friends, become active in local groups, and basically settled into the community.
As a result, I find myself wanting to purchase a home closer and closer to where we live now. In other words, my home searching radius is getting smaller the longer we stay here.
At this rate, if we are still here in another 2 years, I may have to talk Mr. BT into purchasing our rental home =)
Thursday, August 21, 2008
July August 2008 Month's Inventory
Wow, month's inventory is still shrinking! We are now down below 4 months for the Sac Metro area. And while some of the pricey zips still appear to have a high month's inventory, in reality, lower priced homes are in short supply, while the expensive ones sit for what seems like an eternity.
This is good news, and proof that the market is working its way towards equilibrium. It also proves that buyers are out there, so its merely a matter of the market finding price levels that buyers can afford. If they price it right...the buyers will come.

This is good news, and proof that the market is working its way towards equilibrium. It also proves that buyers are out there, so its merely a matter of the market finding price levels that buyers can afford. If they price it right...the buyers will come.

Wednesday, August 20, 2008
Riddle Me This?
How can a home, which has been sitting on the MLS for almost a year, and at the current price for 4 months, without ANY offers, recently appraise at 97% of the value?
I obviously don't understand real estate......
We agreed to pay for an appraisal for the short sale we put an offer on, in order to convince the bank that it wasn't worth what they wanted. The appraisal came in much higher than our offer (which was about 10% off list....our previous offer was 95% off list when interest rates were lower).
Supposedly, the home is now going to go into foreclosure. It will be interesting to see if we are able to purchase it then....
In the mean time, many homes in my favorite neighborhood have come on the market. Two at prices we can afford, and the rest way above our means.
Tuesday, August 19, 2008
Defying Gravity
Zillow came out with some interesting study results this month. Seems most homeowners think that, while home prices are falling in general, their home value is not (as the article points out, its akin to everyone thinking their IQ is above average).
According to ForeclosureRadar, on my street there are:
According to ForeclosureRadar, on my street there are:
- 5 homes in preforeclosure
- 2 bank owned homes
- 2 homes slated for auction
- 7 homes listed on the MLS (3 of which are PS), which includes some of the home listed above.
Monday, August 18, 2008
Update: Driving Home the Debt
A couple months ago I did a post on the WSJ's monthly "hottest models." As some may recall, I was flabbergasted by the price tag on these cars that were so popular.
In another sign of the times, the July 2008 list is a very different list. This time, only three cars had price tags over 30K, as opposed to the vast majority in Feb/Mar. The average price tag for all the models listed has fallen around 28% compared to the earlier time frame!
Not surprisingly, the Toyota Prius tops the list (it was also the only car under 30K on the list in March).
It's Negotiable
Was delighted to see that one of my favorite publications, Consumer Reports (who would have guessed ;) did a recent survey on real estate.
Below is a very interesting conclusion from their study, which is good news for both buyers and sellers (hat tip to the WSJ Developments blog):
"Many real-estate brokers are willing to cut a deal on their commissions, and readers who successfully negotiated for a lower commission, often cutting the traditional 6 percent to 3 or 4 percent, tended to be just as satisfied with the result as those who paid the full fare."
If I had my way, I would completely redesign the compensation system. Here are my thoughts on how commissions should be structured.
Friday, August 15, 2008
A Huge Sigh of Relief
This is my virtual sigh of relief. The week is ending with oil down to $113 a barrel, and the dollar gaining ground. I feel we are now in manageable territory. At this price, industries and consumers should be able to cope.
At $147 a barrel, I believe we were facing economic implosion. The economy was already limping due to housing woes and the credit crunch.....expensive oil and commodities would have been the fatal shot to the heart.
This is not to say we should throw a party. $113 will still be tough going for many industries, like aviation, but 23% is certainly worth a sigh of relief.
Street spam
Is your neighborhood inundated with illegal advertising signs on every corner? The question I have is, who's job is it to remove them? We know the criminals (if you put up an illegal sign, presumably you are a criminal) aren't going to remove the signs.
Although the signs are illegal, Cameron Park Community Services District tells me 'there is nothing we can do about them.' (Of course, IMO, not true, but that is a blog for a different day.)
In addition to being an eyesore, the signs eventually become more litter in our fields and gutters as they are blown down by the wind and weather, most of which appear to have a biodegradable 1/2 life of about 500,000 years, due to the fact they are frequently made of plasticized something-or-other.
I'm not talk about election signs (which are also an eyesore, but protected under the Constitution), or bonafide local real estate signs, or even neighborhood garage sale/lost cat/found dog signs. I'm talking about "Earn millions working from home," "Bankrupty Lawyer" (one of my personal favorites), "We Buy Houses!," "Avoid Foreclosures," Whole House Fans," Humane Rattlesnake Removal," "XYZ Gym and Fitness in Folsom," and so many more.
The Cameron Park area that I drive in is virtually free of the signs. (Wish I could say the same for the portions of EDH and Folsom that I see.) Of course, the criminals still put up the signs, but with apparently less enthiusiasm than time past. I've heard, but have no way of verifying if true, of course, that someone in CP stops his/her car when they see and illegal sign, and picks the sign up for later recycling.
Perhaps if their signs disappear from the horizon as fast as the criminals put them up, word will get out and the criminals will move on, thus making our neighborhoods look more like neighborhoods than litter-bound eyesores.
Just my opinion.
Paul
P.S. Did you know there are actually blogs devoted to street spam, tools for removing street spam, legal issues, etc? Heck, a short while ago, I didn't even know what "street spam" was!
Thursday, August 14, 2008
The Growing Gap
I haven't reported on my screen scrape in some time. Several interesting things of note.
The number of homes pending sale has jumped again. We just hit a new record high, at my scrape yesterday. While the total number of homes meeting my criteria is still very high, the pending sale, and short sale homes make up the bulk of the listings these days. The list price differentials between the categories is what is the most interesting.
Average list price per square foot for homes in Folsom and EDH that meet my criteria -
Pending Sale -$174
Short Sale - $174
REO & Normal - $189
Thus, even though there are tons of homes for sale in the area, there is very little of interest on the market worth pursuing, except a couple REOs. We are attempting to negotiate a short sale, but my expectations are very low at this point.
Wednesday, August 13, 2008
Updated Market Stress for Folsom and El Dorado Hills
Below is the updated market stress data for Folsom and El Dorado Hills. The NODs had leveled off for both zips for a while, but this week saw a renewed upward trend. I included some additional data this week for context, such as REOs listed on Metrolist (which includes the REOs that are Pending Sale), to get a feel for the level of shadow inventory as discussed on SacRealStats.
I should note that none of these data sets are complete, and they don't all necessarily overlap the way they should. But I think the magnitude of the data is about right, and that relative comparisons can still be made. For example, the SFH listings, from ZipRealty could be subtracted from the Total MLS listings, to get a relative feel for how many homes are currently pending sale in each zip. The REOs could be subtracted from the foreclosures to determine the level of "shadow" inventory etc.
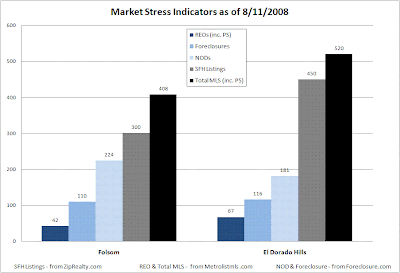
I should note that none of these data sets are complete, and they don't all necessarily overlap the way they should. But I think the magnitude of the data is about right, and that relative comparisons can still be made. For example, the SFH listings, from ZipRealty could be subtracted from the Total MLS listings, to get a relative feel for how many homes are currently pending sale in each zip. The REOs could be subtracted from the foreclosures to determine the level of "shadow" inventory etc.

Tuesday, August 12, 2008
Bemoaning the Budget
Since budgets are all the talk right now in Sacramento, I thought it would be a good topic for the day.
When average folks have a goal, like home ownership or early retirement, the standard advise seems to be "make a budget". To me this is a lot like the "food diary" advise for weight loss. Nice in theory, but just way to intrusive and hard to keep up for a busy family.
I do reconcile our credit cards, bank statements, etc. in Quicken every couple months. I also categorize the purchases, but there are many items that fall outside a normal budget (like loans to family, or work expenses), or ATM cash that just disappeared. I have tried on several occasions to use the budgeting functionality in Quicken, but for some reason or another, it doesn't get me what I am looking for.
This leads me to wonder, does anyone actually have a household budget and if so, do you follow it?
There are many categories, in which I am unsure about how much to budget. For instance, how much to give to charity, how much should we allocate in gifts to family and friends, how much for travel and vacations?
Both Mr. BT and I grew up in families that struggled to pay for basics like food and clothes during some periods of our lives. This environment shaped our financial habits. We don't buy on credit unless we can pay off the bills immediately. Now that our massive student loans are paid off, we have relaxed the reigns a bit and spend a bit more freely.
I have an idea how much we spend on things, but I don't know if its above average, or if we are really pinching pennies. Talking to my uncle, who's family makes considerably less than us, I feel like we really pinch pennies on things like food, auto and cable bills compared to them. But I don't know if they are over spending, or if we are underspending.
With finances a somewhat taboo subject among friends and colleagues....how do people figure this stuff out?
Sunday, August 10, 2008
The Family Treehouse
Here is a quick rundown on how my immediate family has been affected by the housing bubble. Increased affordability has helped my mom and dad (separately) become homeowners again, but unfortunately it will be a struggle for my younger brother to hold on to his home.
- Mom, Santa Maria CA, just bought a home with her long time boyfriend, paid cash, retired.
- Brother, Aliso Viejo CA, has lost all equity on the home he and is wife purchased in 2005. Their ARM will adjust in 2 years, to approximately 50% their income. It will be difficult to work something out with the bank since they took out a 2nd when purchasing the home.
- Father, Puerto Vallarta/Stocton CA, moved to Mexico from Stockton around 5 years ago, now purchasing a bank owned home in Stockton. Currently under contract. Retired.
Friday, August 8, 2008
It's Even More Official
The job losses are mounting.
My uncle, the printer, who has been living in the Sacramento area for almost 20 years, tied the knot this year. Unfortunately, the good times were sort lived. I am deeply saddened to report that his new wife, has been laid off without warning, after working at a local Sacramento business for 19 years.
She is the second family member in the area to be laid off recently.
I am at a loss for words to describe how I feel right now.
August 2008 Inventory
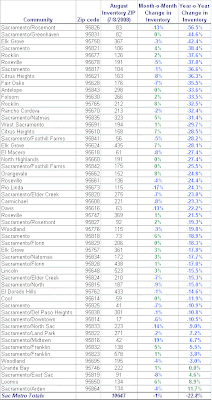
Inventory is somewhat steady compared to last month, but is still down 22% compared to last year. This month's data is sorted by the biggest drop compared to last year. Data was collected from ZipRealty site for SFHs. The increases are in green, and decreases are in blue.

Thursday, August 7, 2008
Sacramento Airport Activity Reflects the Region's Troubles
Max over at SacRealStats has been documenting his experience at several airports in CA.
Since aviation is my industry, I thought I would take a quick peak at our regions airport statistics for June of 2008, which is the most recent data they have on their webpage: http://www.sacairports.org/int/about/stats.htm
I don't have good news to report. Activity at our local airports is experiencing substantial declines. This is not a good sign for our region and our economy.
Sacramento International -
Passenger traffic is down 6.4% over last year.
Operations are down 10.4%.
Mather Field -
Operations are down a whopping 25.2% (with general aviation taking the biggest hit)
And operations at Sacramento Executive Airport are down 15.7%.
Update: I just checked the FAA's Terminal Area Forecast....from 2007 to 2008, SMF was actually supposed to grow operations by 2.3%! I guess we will be seeing some revised forecasts.
Market Manipulation
As many of you know, I have a strong hunch that Wall Street insiders and speculators are responsible for many of our recent bubbles (they manipulate the market and make a killing at the expense of the "ignorant masses").
This recent revelation by Reuters does little to quell my conspiracy theory leanings....
"A quiet data revision that has boosted by nearly 25 percent the number of oil futures contracts U.S. regulators think are held by speculators is raising eyebrows in the energy trading community. The revision means that speculators controlled 48 percent of the open interest in NYMEX crude oil futures and options as of July 15, compared with just over 38 percent under the previous classification.......The big shift is all the more surprising, oil traders and analysts said, since the CFTC apparently reclassified only one unidentified oil trader at the same time as the data revision."
I am quickly losing confidence that our free market society provides equal benefits to all involved. U.S. regulations and over site are out of date, and too disjointed to properly monitor the market and ensure that it is free of manipulation. Those with connections and resources routinely increase their wealth, while those without are left to foot the bill for the market's excessive risk taking.
Wednesday, August 6, 2008
We can Out-Wait, but can we Out-Wit?
Some may remember the short sale we agonized over this spring. In the end we decided not to go up in price and meet the bank's price. Our waiting strategy may pay off yet. After many months of sitting at the bank's (first loan's) price, we are going to resubmit our offer (albeit adjusted for the increase in interest rates).
Last Sunday we did see an REO that is amazing, and in our price range (the one on Moonstone in EDH). But they want us to go through all kinds of prequal and legal hoops, and the bank who owns it is Option One (not excited about dealing with them again). Our realtor figures it will go for much more than asking, so we are not inclined to go through all the hassle in order to get outbid.
I am also kinda still kicking myself that we didn't go up a bit on the last REO we bid on. It was basically in move in condition with lots of gorgeous tile and granite work. Sigh.
Sunday, August 3, 2008
As the Endgame Draws Near
According to Webster's "endgame" is the final stage of a game of chess, usually following the exchange of queens and a serious reduction of forces. This term seems appropriate for the eventual fate of this blog as well as many other RE bubble sites.
In that past couple months, many longtime bubble bloggers have purchased, or are currently purchasing a home, as prices in the Sacramento area have come back down to earth.
This leads me to wonder, what is going to happen to the vibrant community of bubble bloggers? Looking at all the links on Lander's site, its a sizable cottage industry =)
As for this blog, sometime in the short term, we hope to buy a home. If we don't, I suspect it will get really lonely around here, as many will have preceded us.
But what I am really curious about is the long term. In the long term, all the housing bubble sites will be obsolete. I suppose some sites with a large economic base, like CalculatedRisk, could evolve with the times.
Obsolesce is awkward. It's like the mom's I see around here, who, instead of aging gracefully, are still trying desperately to be hip and young.
When my time comes, I already know it will be hard to let go of something I have diverted so much energy and time to. This waiting game is a lot like being pregnant. The end product makes the wait worth the while (although this time we have waited longer than both pregnancies combined!).
Covered bonds, the next taxpayer bailout
Although too long and probably not suitable for including in a post, you are all encouraged to read "Covered Bonds, Exposed Taxpayers" in the current issue of Business Week. As sure as bears use Charmin in the woods, this will come back to bite us in the future.
In short, banks issue mortgage back bonds to finance real estate loan purchases. The loans remain on the banks' balance sheets, thus, if the bank fails, the loans are repaid to the investors ahead of payments to the FDIC. If there are insufficient assets to repay the FDIC, the FDIC takes another financial hit. Enough financial hits to the FDIC, and we are back to the taxpayer paid S&L bailout of 1990. FDIC Sheila Bair, who is a very bright lady and understands these risks, has limited banks exposure to 4%, but Treasury Secretary Paulson and the banks want higher limits for "increased liquidity." If we have learned nothing else in the past three years, "increased liquidity" is nothing more than code words for indiscriminate loans to increase short-term corporate profits, to heck with what happens to those loans in the future.
Paul
Thursday, July 31, 2008
My Prediction, Part II
Okay, not really a prediction, but it seemed to tie to yesterday's post.
I use Radarlogic to monitor local price trends. Not perfect, but it allows me to compare prices over time. For example, current (May 31, 2008, because Radarlogic lags 60 days) Sacramento MSA price is the same as March 2003.
Again, I don't know where prices are going to go, but I feel comfortable in predicting a minimum 10% additional decline (and possible additional 20% decline, all on a local level, of course). A 10% decline, per Radarlogic, would take us back to May 2002 home prices. A 20% decline would take us back to May 2001 prices.
If we see 20% further local declines (which I am not predicting but could happen), that would mean that everyone who bought after March 2003, even with 20% down, would have negative equity. Pretty discouraging numbers, but certainly motivation to be a patient renter.
Wednesday, July 30, 2008
My prediction
I don't profess to know what is going to happen 5 minutes from now, let alone next week, next month or next year. But that doesn't stop me from having beliefs that only time will tell are right or wrong.
Tomorrow is the last day of July. I think a lot of sellers have been holding off dropping prices over the summer, hoping to find a buyer who is participating in the claimed summer buying binge. Now that we are about to enter the month of August, I think we will start to see a small amount of capitulation and many of those sellers (read: banks) will make significant price reductions to try to capture a buyer before the market goes into the autumn/winter doldrums.
What is your prediction?
Paul
Tuesday, July 29, 2008
More than a little irony
As you have no doubt heard by now, last night Merrill Lynch sold +$30 billion in mortgage backed securities for $.22 on the dollar. Personally, I think this is a big deal for several reasons. First, it forces other CDO holders to mark their securities down to $.22 on the dollar (read: More write downs to come). Second, I am guessing this is close to the floor for markdowns on CDOs, after all, how much lower can the price go after a 22% mark down?
But what I find interesting is that Merrill sold the approximate $6.7 billion in CDOs, to a buyer who paid only 25% down with Merrill financing the balance. Now admittedly this is better than the 100% home financing that got Merrill into this situation, but the 100% home financing was in a rising home price market, whereas the 75% financing of the CDO's are in a declining CDO price market (Merrill valued these CDO's at +$11 billion only 28 days ago). So will Merrill soon be foreclosing on the CDO's that it just sold, while the CDO's are foreclosing on the underlying homes?
Paul
Sunday, July 27, 2008
The "stealth" bailout
You all know about the $300 billion "Stick it to your Children Act of 2008," but have you done the math for the rest of the bailout (so far)?
From CNBC:
1. Gone (in the past 12 months) from the Fed's balance sheet, $311 b in treasuries, used for such things as auction rate securities to Wall Street banks, bailout of Bear Stearns, etc.
2. Federal Home Loan bank "advances" to members using members' mortgage securities as "collateral," $284 b.
3. Mortgage securities purchased by Fannie/Freddie in the past 12 months, or so, $621 b.
4. Added to FHA (unrelated to the legislation passed this week), $90 b.
Total per CNBC, $1.43 trillion. (I know, my numbers don't add up. If you read the original CNBC article, you will see why my numbers are actually less.
Maybe all of these billions will be repaid. Maybe not. As someone in my office opined, we need to make more children to help pay these future debts off!
Paul
Friday, July 25, 2008
Historical Housing Statistics along Highway 50 in Sacramento
As I mentioned yesterday, I'm a little burnt out on our home search and depressed about our prospects for finding a home anytime soon......
So instead I am generating some data to keep idle Friday workers entertained. Below is the monthly DataQuick sales count, median price per square foot, and median sales price data I have collected from the SacBee website for the major zips along Hwy 50 in Sacramento (95819, 95826, 95827, 95670, 95630). As with all my SacBee DQ data, I don't have any means of updating it (like when DQ changed their methodology), so for the record I am not making any representations as to the data's accuracy.
Feel free to post Zip requests. I will try and fill them next week.


Thursday, July 24, 2008
Seven Cent Solicitation
I just don't have much to say lately and am on on a deadline...so feel free to post RE related thoughts.
I would be especially keen to hear everyone's seven cents on the recent Housing Legislation passed by Congress. My hope for a veto was recently extinguished.
At least there are some provisions for first time buyers...but they look a bit complicated at first blush (and could anyone figure out the definition of a first time buyer...it tends to vary by context?).
I will try and post some historical data on different Sacramento zips in the coming days to fill some space.
(Why not two cents? According to Webster's "two cents" tends to be unwelcome/unsolicited advise, so I figure I'm inviting comments, coupled with inflation, and a bit of tongue twister....and voila.....seven cents.)
Wednesday, July 23, 2008
The Power of Averages
Some may be familiar with the anecdote of when Sir Francis Galton visited a livestock fair in 1906. While there, he stumbled onto a contest where villagers were to guess the weight of an ox. He found that if he took the average of all the guesses, it came within one pound, even though no one's guess was correct.
All this to say, I am a little disappointed that the average of all the experts didn't quite work out in this situation. I am continually stunned by the fact that so many "experts" were blindsided by the housing and mortgage bubbles.
If you ask me, most were clueless because they were so out of touch with average Americans. If you are working 80 hours a week, and only hang out with like minded individuals (often from the same profession), you have no way of knowing the struggles average people face. As I stated in an earlier post, Wall Street does not know the lives behind the Main Street data. The data can only tell you so much. When things were good, no one felt the need to look beyond the data.
This is where I have always had the upper hand. I'm the type of person who will start chatting you up in line at the supermarket to pass the time. I was also that person in high school who refused to stick with one particular group of friends (the jocks, the ags, the surfers, the goths etc). I have family all over the state in many lines of work (some blue collar, some white collar) and I love to listen to people's stories (which is ironic since I tell mine on a daily basis).
So yes, I have a masters and can analyze data, but I also read columns from various new sources (not just gloom and doom blogs), and listen to what average people have to say. Of course I sometimes get worked up reading the housing bubble blogs, but I try hard to keep an open and objective frame of mind.
Tuesday, July 22, 2008
Did you ever have that feeling?
I have toured houses that were for sale, and my skin crawled because they were so dirty. I have toured houses where I knew a death had occurred, with no particular reaction other than sadness over the loss of life. When I have listened to others tell me about their "dark feelings" in a particular house, I have tended to be cynical and mostly polite, thinking of a house as a commodity and shelter, free from the evil forces that Hollywood movies conjure. This all changed when I walked into an otherwise unremarkable home on Sunday afternoon. I do not believe I have ever in my life felt such a dark and deathly force overcome me. I don't know anything about that home's history, but I was shocked at both the existence of the feeling and the overwhelming magnitude of the feeling. I immediately grabbed Mrs. Paul and almost ran from the house, not explaining the "why" to her until we were safely in the car.
Maybe I've turned into a "kook" after all?
Maybe I've turned into a "kook" after all?
Monday, July 21, 2008
Folsom & El Dorado Hills Historical Home Sales Data - June 2008 Update
Below are the latest sales and $$ charts for Folsom and El Dorado Hills. The downward pricing trend is continuing. We are now at $183 median price per square foot in EDH! Not nearly as promising in Folsom, which stands at $206 as of June. Hence we have just about stopped looking in Folsom, since we can get much more house for the $$ in EDH.
Sales in both zips seem to be leveling off a bit, which is why the year-over-year numbers look so promising. One of the main reasons I look at the data over a longer time horizon is because y-o-y numbers can be very misleading. Comparing a bad year to another bad year, doesn't give enough context for the data.
Anecdotal note: Was out for my usual walk with the kids yesterday afternoon, and saw a piece of paper taped to the door of a house we always pass. I didn't go up to check, but I have a strong feeling it wasn't a cookie recipe from a neighbor. This home wasn't even in my www.foreclosureradar.com data. With the HOA maintaining the outside of homes in Serrano, there isn't much to outwardly indicate financial stress. So its always a bit of a shock for me, as opposed to a predictable progression.


Subscribe to:
Posts (Atom)

 Posts

